目录(6 节)

·
Robinhood Chain Earns Under 0.4% of Revenue. Why Did Robinhood Build It?
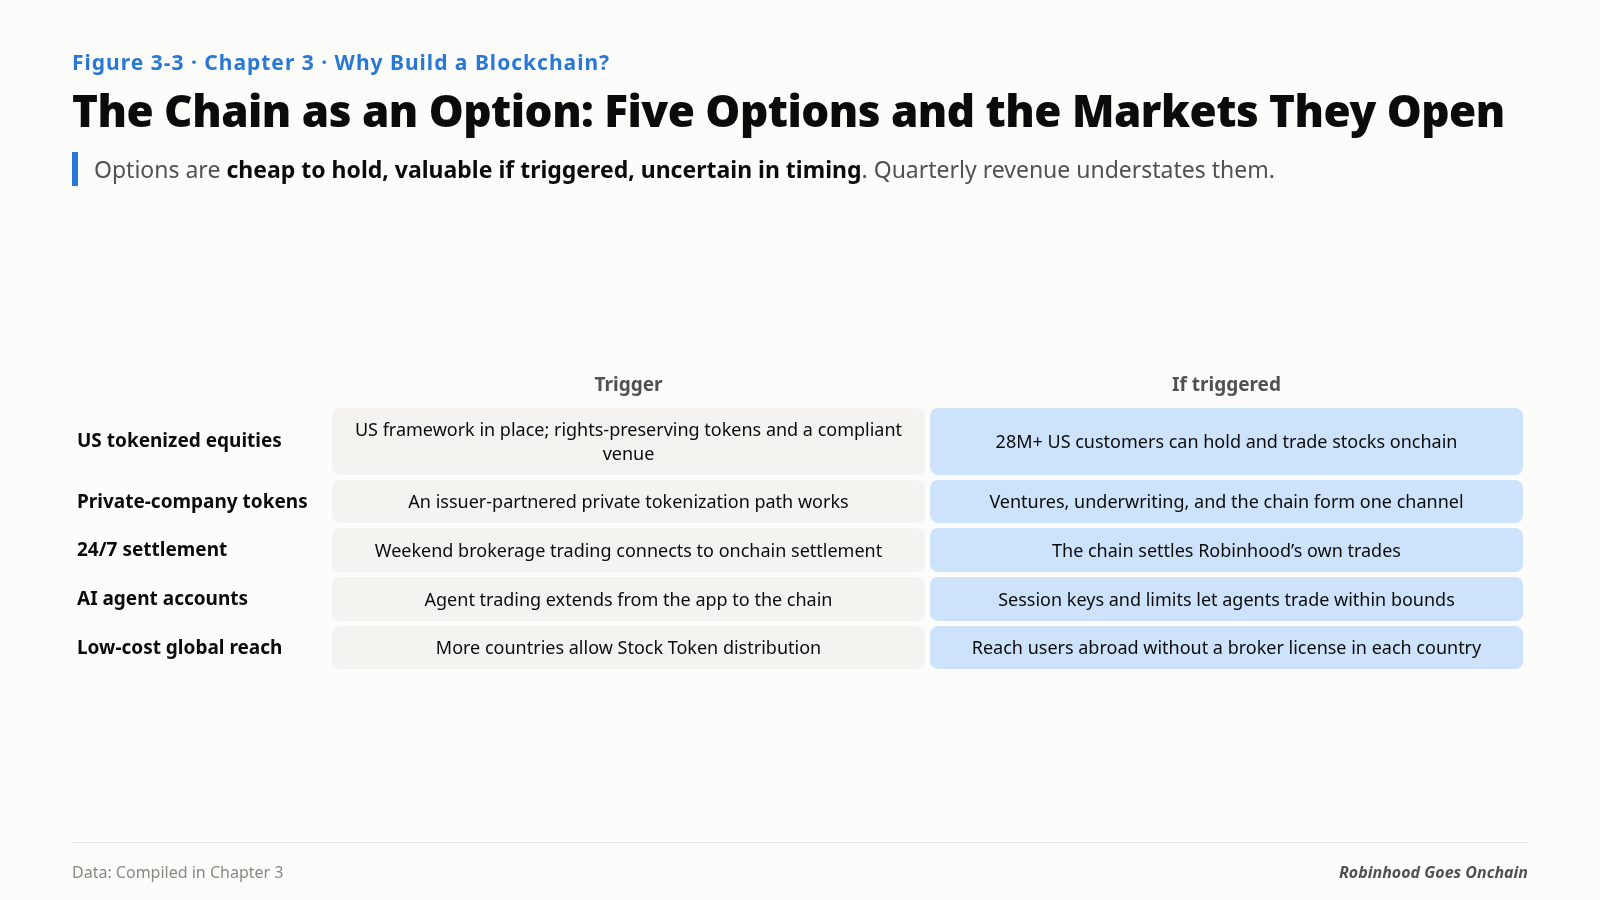
Robinhood Chain's revenue fell to under 0.4% of Robinhood's revenue by October. Measured by sequencer fees, it wasn't worth building. Read as the fourth barrier Robinhood is removing, it is a portfolio of options: tokenized U.S. equities, private-company tokenization, 24/7 settlement, AI agent accounts and low-cost international distribution.
If you work at a broker, a bank or a fintech company and your team is debating whether to build its own blockchain, Robinhood Chain is the case worth taking apart right now.
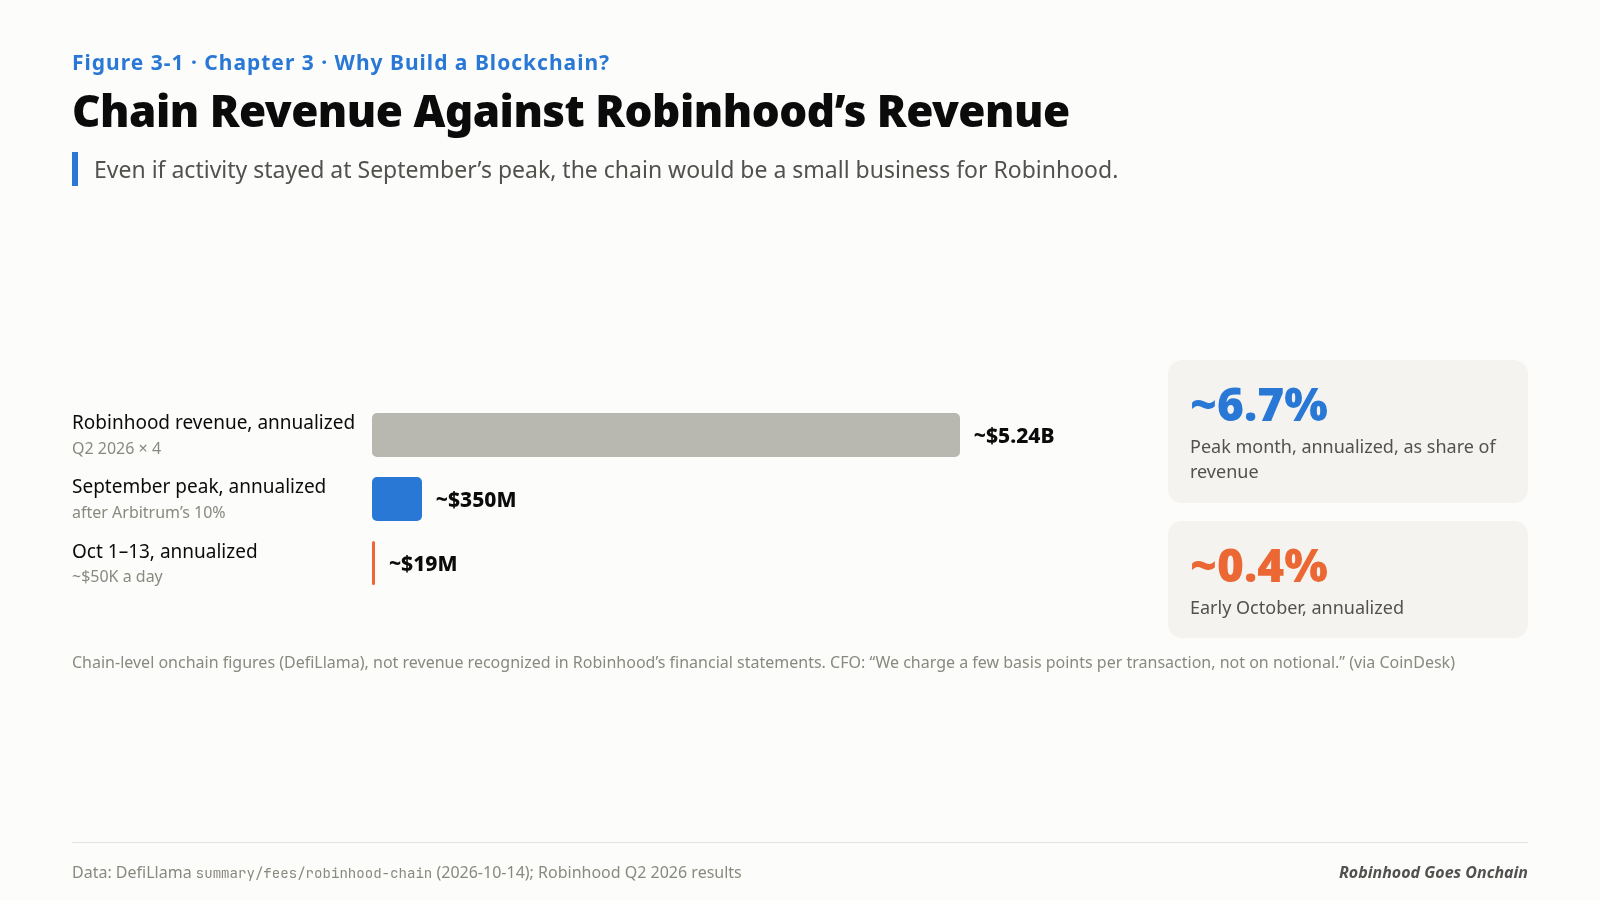
Start with the numbers. September 2026 was the chain’s busiest month since launch. By DefiLlama’s chain-level count it generated about $35.93 million in sequencer fees; after the cost of posting data to Ethereum, net protocol revenue was roughly $32.31 million.
Now set that against Robinhood itself:
- Q2 2026 net revenue was $1.31 billion, about $5.2 billion annualized.
- Annualize the September peak and subtract the 10% owed to the Arbitrum ecosystem, and you get roughly $350 million, or 6–7% of revenue.
- From October 1 to 13, chain-level revenue fell to about $50,000 a day. That annualizes to a little over $18 million: less than 0.4% of Robinhood’s revenue.
These are chain-level figures, not revenue Robinhood recognizes in its financial statements, and the company does not report the line separately. The order of magnitude is still clear. Even if activity stayed at September’s peak forever, the chain would be a small business.
Judged by sequencer revenue, the chain was not worth building. Robinhood built it anyway. The problem is the ruler.
The Fourth Barrier
Look back over Robinhood’s decade and it has been doing one thing: turning barriers into products.
| Barrier | The old model | Robinhood’s approach |
|---|---|---|
| Price | A commission on every trade | Commission-free trading (2015) |
| Minimum investment | Enough money for a whole share | Fractional shares |
| Time | Trade only while the exchange is open | 24-hour trading from 2023; weekend trading announced, subject to regulatory review |
| Borders and custody | International users need a U.S. brokerage account | Stock Tokens, a self-custody wallet and Robinhood’s own chain |
The first three barriers were removed inside the U.S. brokerage system. The fourth is the edge of that system. Stock Tokens lower the barrier of opening an account and holding the claim; the underlying shares still sit with a custodian. What changes is the form in which users hold a claim tied to them.
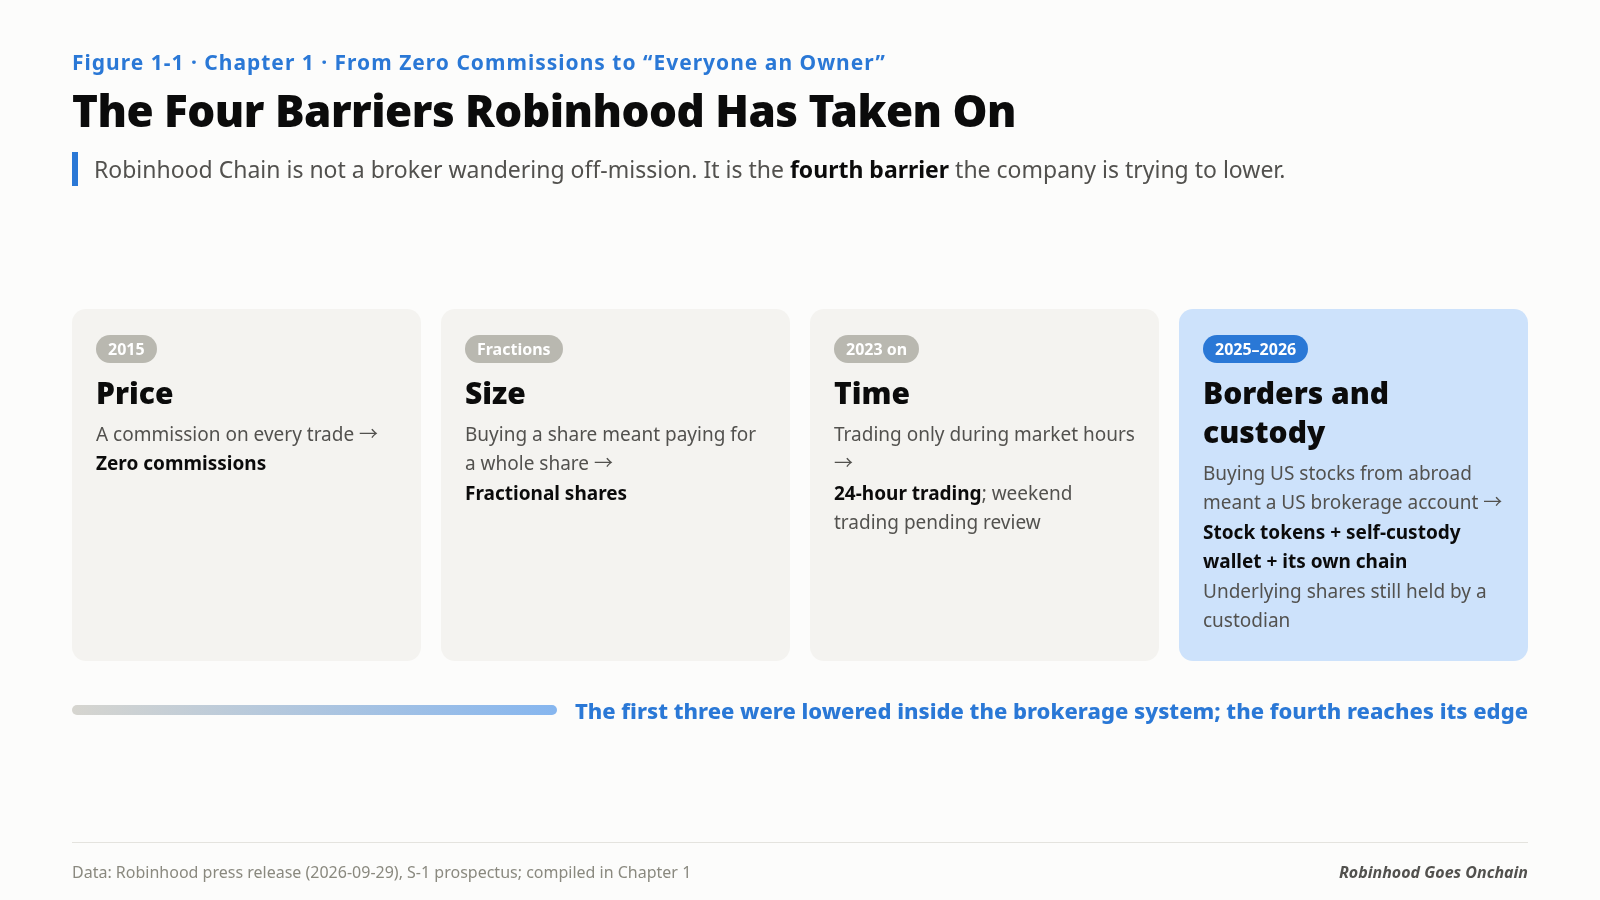
So Robinhood Chain belongs in the sequence of barriers the company has removed, not in a league table of competing blockchains. Its competition with Base or Solana is about assets and distribution, not raw speed.
Two details from Q2 2026 support that reading. Crypto transaction revenue fell 38% year over year while event-contract revenue grew more than tenfold: the growth engine of the moment was not crypto, let alone the chain. In the same quarter, international funded customers passed 1 million for the first time, still under 4% of the total. The chain was not built to replace the U.S. brokerage business. It was built to open markets outside the United States and to prepare infrastructure for the next generation of products.
A Tension Worth Facing
Payment for order flow is one of the main sources of revenue behind zero commissions, alongside net interest, subscriptions and other transaction revenue. They share a premise: customers trade inside the app and leave their assets there.
Once customers move assets into a self-custody wallet and trade on a decentralized exchange, that in-app revenue may no longer accrue to Robinhood.
That explains the onchain route it chose: international users first, products embedded in its own app first. The chain is not a way to let customers walk out. It is a way to keep the part after they step outside on ground where Robinhood sets the rules.
Four Things a Chain of Its Own Buys
If direct revenue is modest, why not deploy on Arbitrum One or Base, as the first generation of Stock Tokens did?
The answer is control. A chain of its own gives Robinhood four things it could not get to the same degree on a general-purpose network:
- Ordering rules. The documentation describes first-come, first-served ordering with no public mempool, which limits the sandwich attacks common on Ethereum mainnet. In October, CoinDesk reported that Robinhood was evaluating Arbitrum’s Priority Gas Auctions. Which policy to run is Robinhood’s call.
- Compliance tools. The operator can filter certain transactions or restrict particular wallets when needed, a capability a regulated firm relies on to comply with sanctions and legal orders.
- Targeted subsidies. Gas is waived only for swaps initiated in Robinhood Wallet, so the subsidy goes precisely to its own users.
- Upgrade timing. Upgrades follow Robinhood’s product calendar rather than a DAO’s governance process.
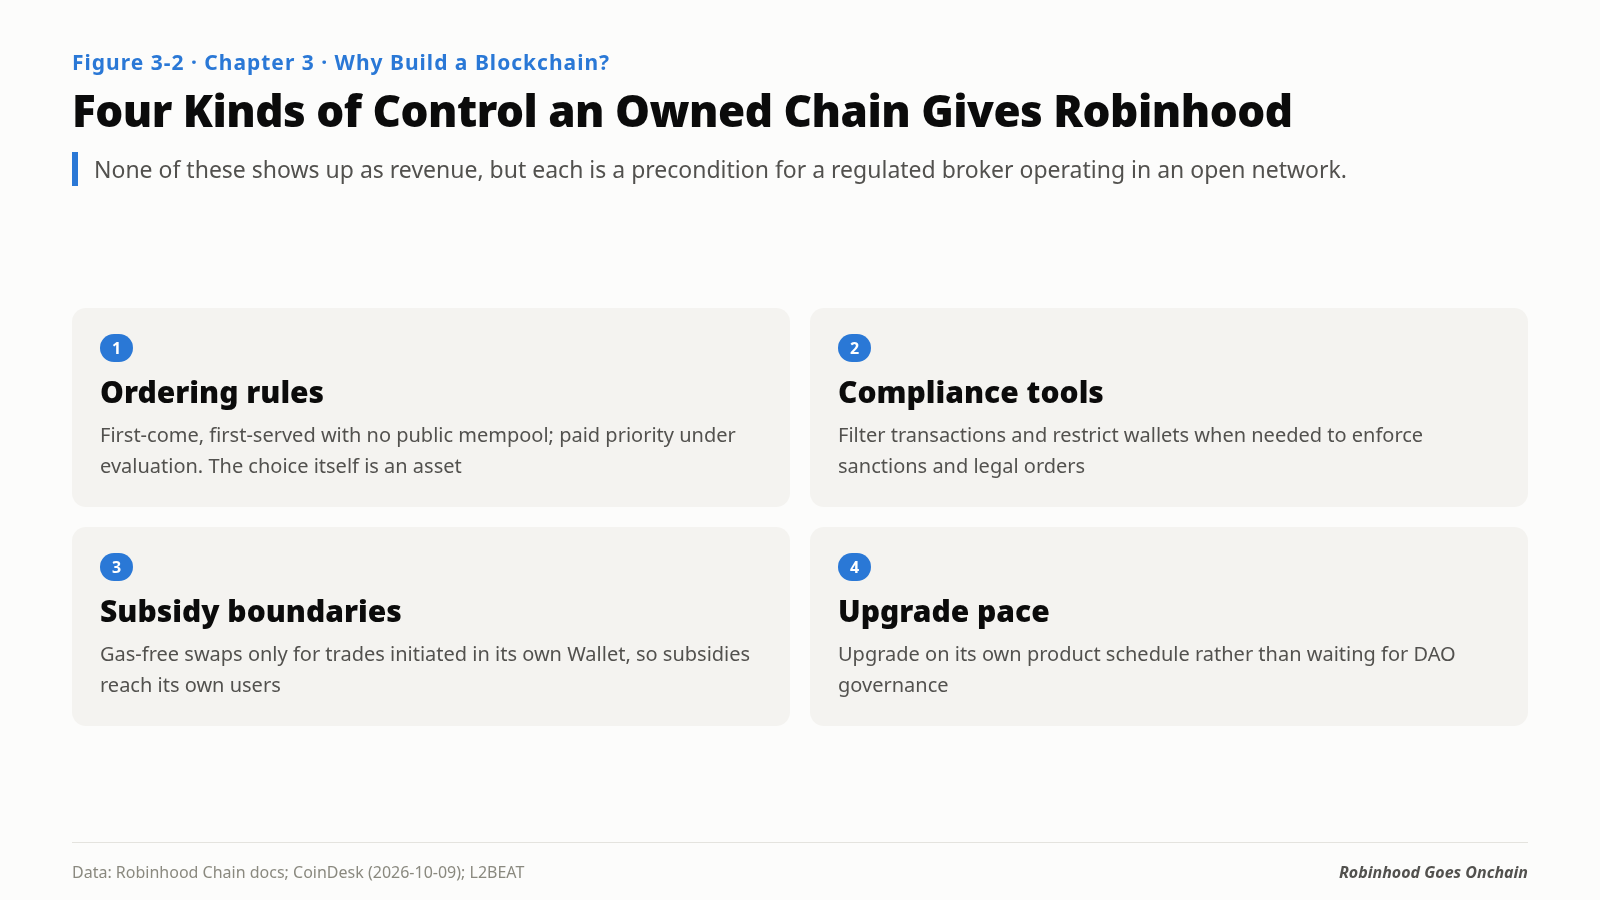
None of the four appears on the income statement. All four are preconditions for a regulated broker doing business on an open network.
The Framework: The Chain Is an Option, Not a Profit Center
Compressed into one line: Robinhood Chain’s value to Robinhood lies mainly in a portfolio of options, not in a profit center.
| Option | Trigger | What exercise would mean |
|---|---|---|
| Tokenized U.S. equities | The SEC framework becomes operational; Robinhood launches rights-preserving tokens and a compliant venue | 28 million-plus U.S. customers could hold and trade stocks onchain |
| Private-company tokenization | An issuer-supported path for tokenized private securities works | Robinhood Ventures and the chain become one channel from pre-IPO to public trading |
| 24/7 settlement | Weekend brokerage trading connects to onchain settlement | The chain settles Robinhood’s own trades, not just third-party ones |
| Financial accounts for AI agents | Agent trading moves from the app onto the chain | Agents transact within session keys and spending limits |
| Low-cost international distribution | More countries allow Stock Token distribution | Reach users without a full brokerage license in each country |
Options share a profile: cheap to hold, valuable if exercised, uncertain in timing. The cost of building, running and subsidizing a chain is small next to Robinhood’s revenue. If the tokenized U.S. equities option becomes exercisable, the chain’s value changes by an order of magnitude.
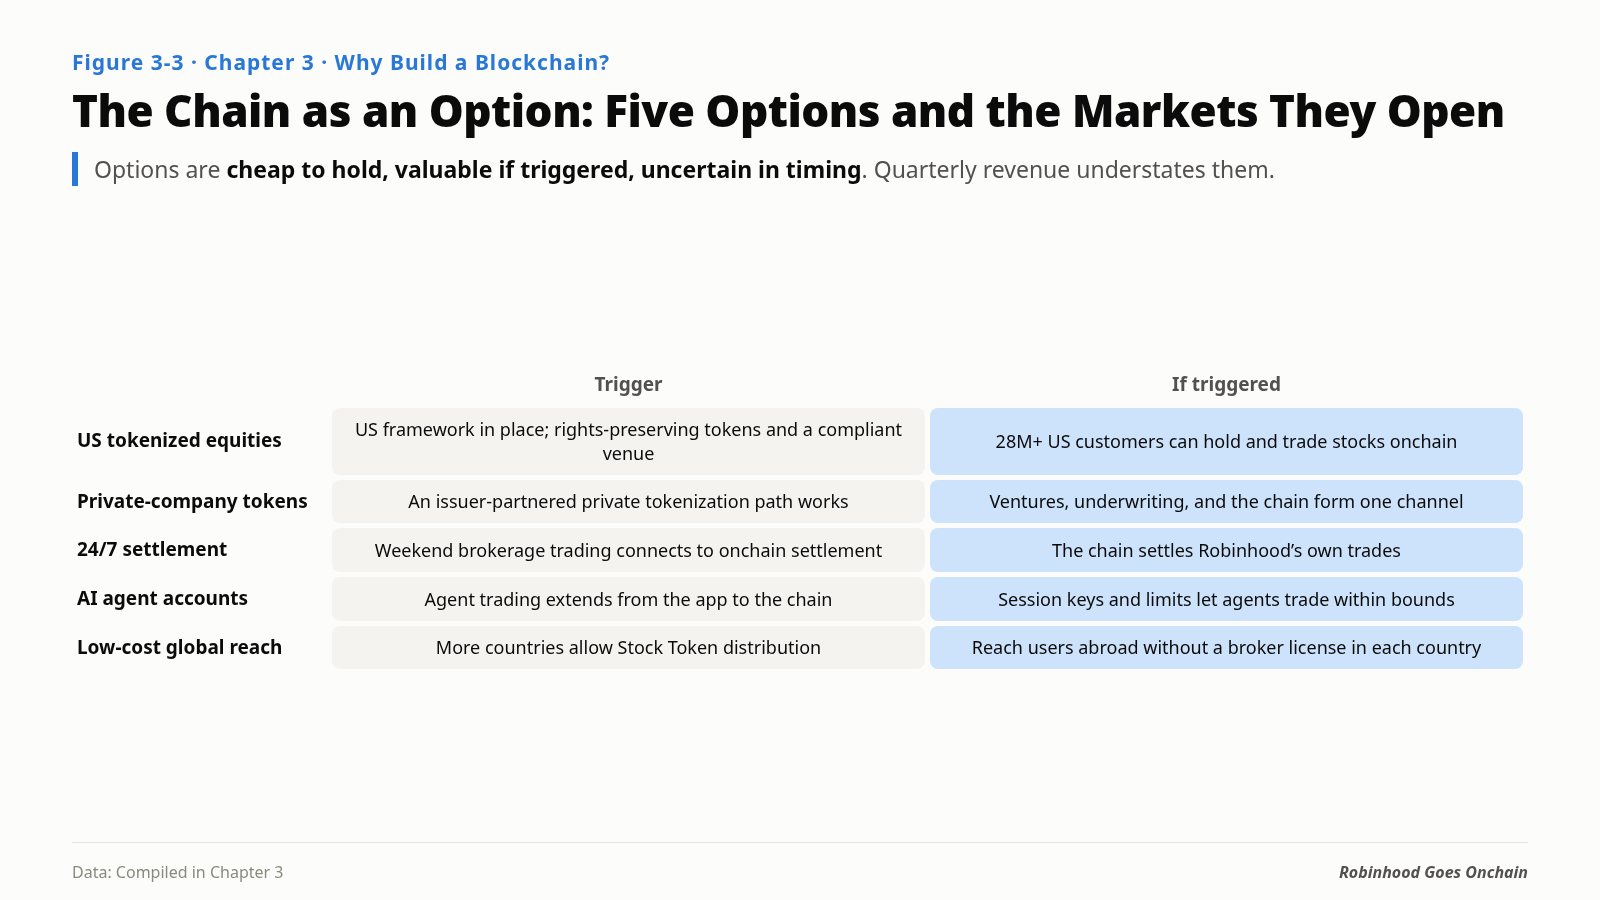
Valuing the chain on quarterly sequencer revenue is like judging an unexpired option by today’s quote.
Analysts split along exactly these two views. Bernstein offered a scenario: by 2028 the chain could generate as much as roughly $160 million a year in fees, if stock-token trading grows as a share of network volume. Morgan Stanley, as summarized by TheStreet, stressed distribution: 28 million customers who already trust the platform give Robinhood a “right to win” in tokenized finance. One measures a business, the other a strategic option. Both rest on assumptions, and neither is a floor or a ceiling. The long-term case for HOOD depends on whether, and when, the second kind of value is realized.
If You Are Considering Your Own Chain
- Decide first whether you want revenue or control. For fee income alone, deploying on an existing network is usually cheaper. A chain of your own makes sense when you need ordering rules, compliance tools, subsidy boundaries and upgrade timing.
- The expensive part is no longer the technology. Arbitrum and the OP Stack have made launching a chain cheap; bootstrapping liquidity and an ecosystem is what costs.
- Argue with an option inventory, not a revenue forecast. Give each option a trigger and an observable measure, so the board has something to track.
The Takeaway
Sequencer revenue answers “How much does the chain make today?” The option inventory answers “Why own a chain at all?” Robinhood is betting on the second question.
If your institution built a chain, what would be the first option on its list?
— Adapted from Robinhood Goes Onchain: A Broker’s First Year, Chapter 1, “From Zero Commissions to ‘Everyone an Owner’,” and Chapter 3, “Why Build a Blockchain?”
The full book (17 chapters, 48 figures, first 3 chapters free to read): https://pickful.ai/books/qx7q
转发此帖子?
与您的关注者分享。
回复