
Contents (6)

·
Holding vs. Using: $2.9B of tokenized stocks onchain, only $18.9M lent against them
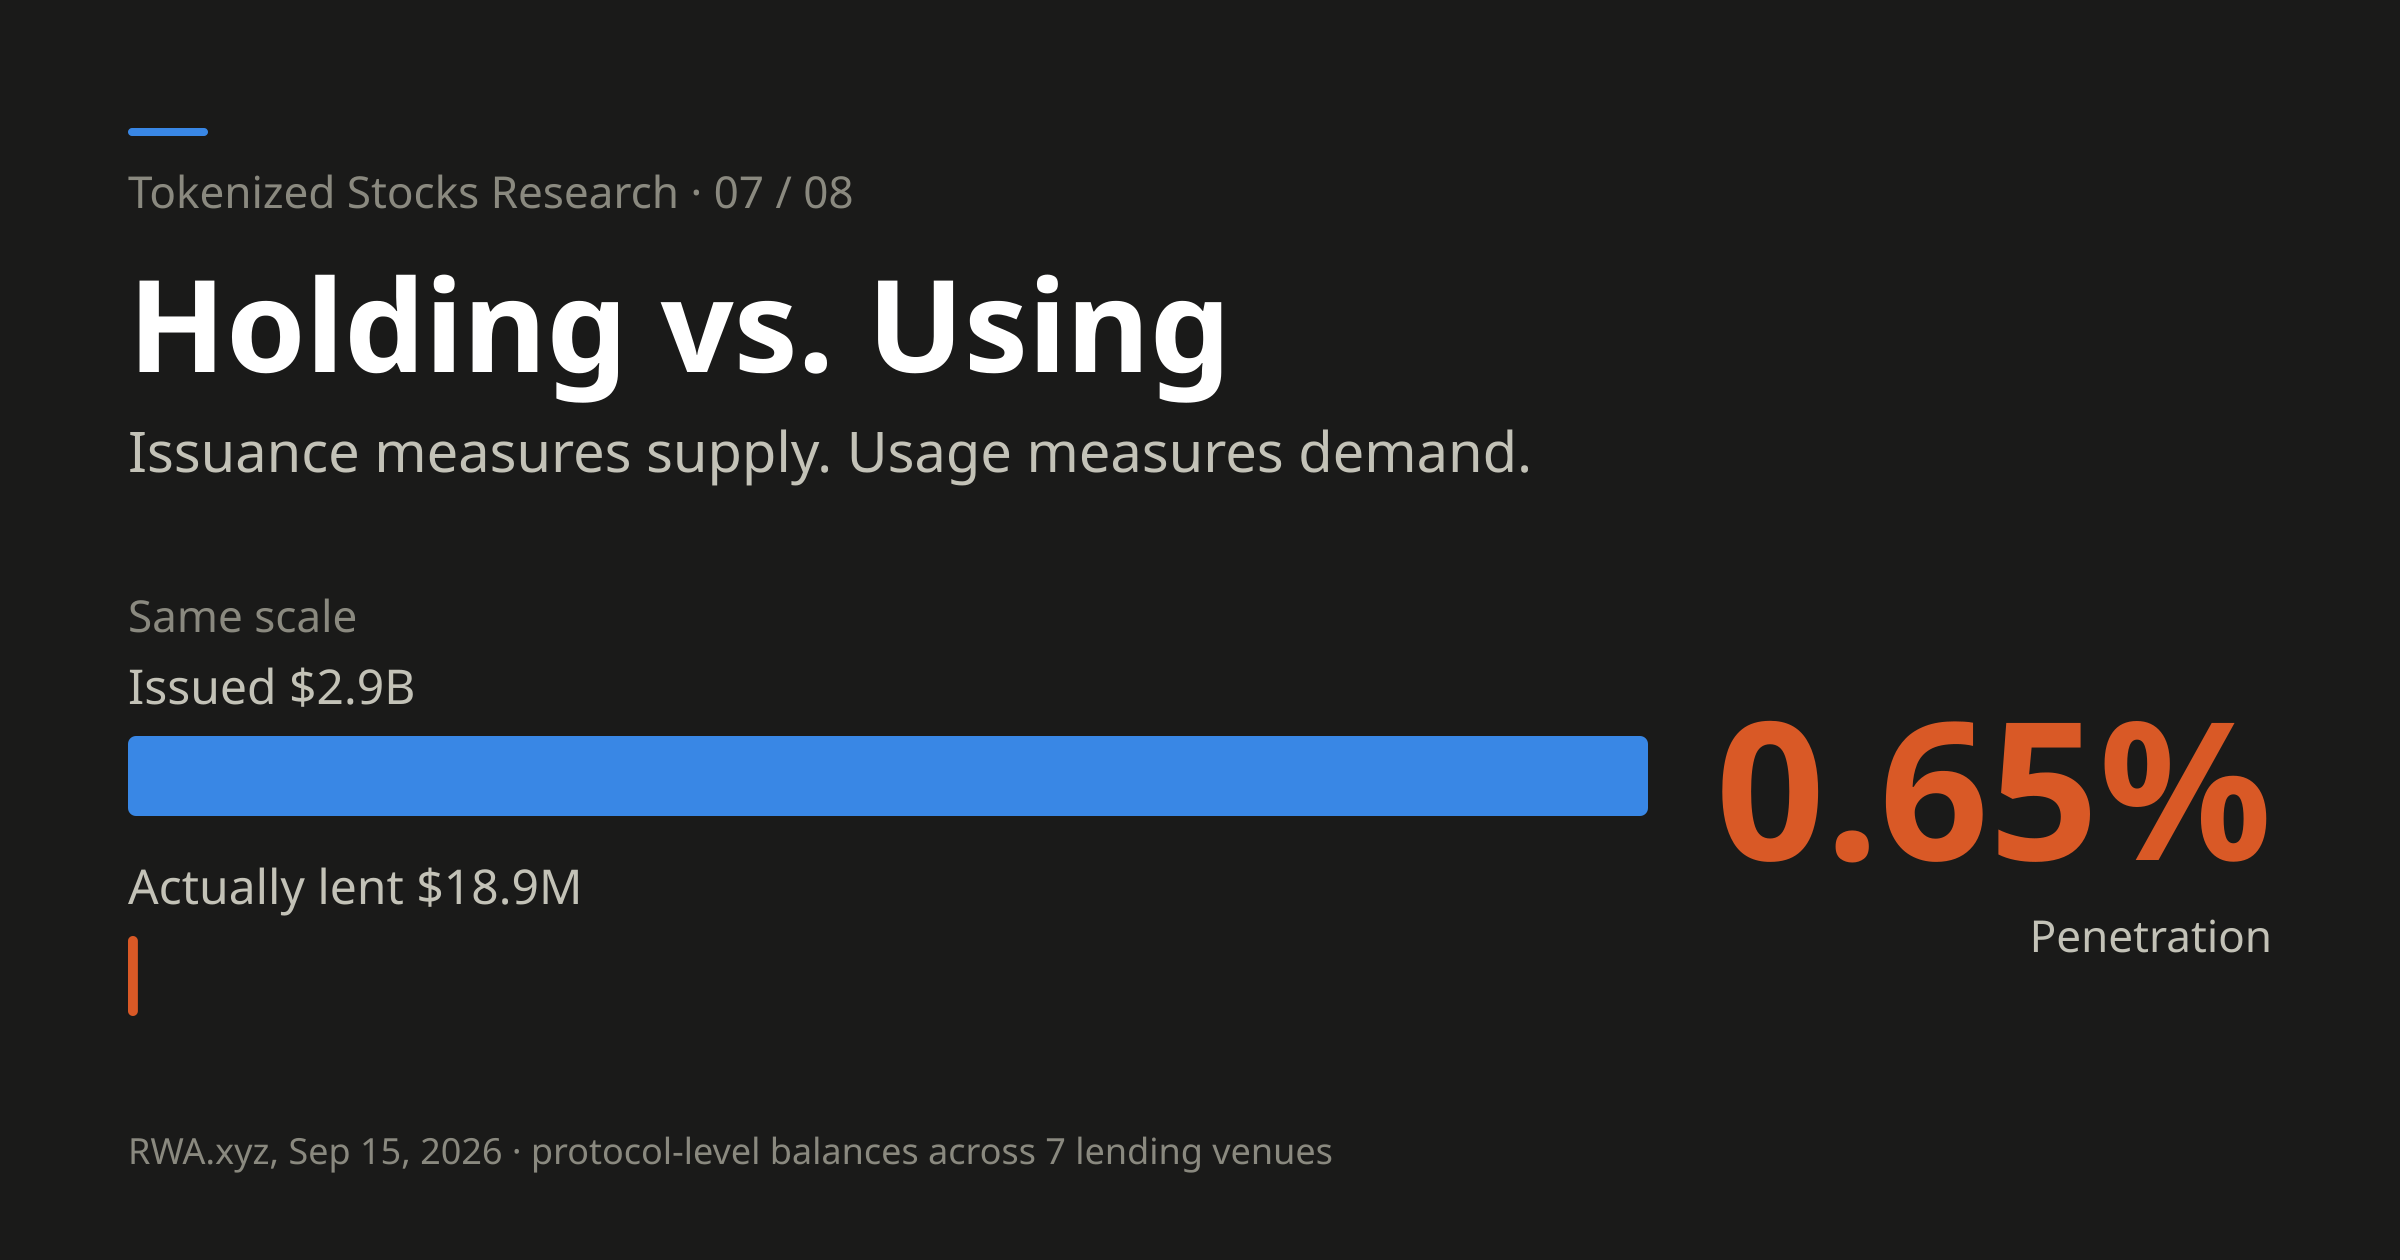
There's about $2.9B of tokenized stocks onchain, and about $18.9M of credit lent against them: 0.65% penetration. Issuance measures supply, usage measures demand, and the industry mostly publishes the first.
If you’re looking for a gap in the market nobody has filled yet, or trying to judge how much of the “RWA composability” story has actually happened, this gives you a number you can calculate.
The stock of tokenized equities is no longer small: about $2.9B (RWA.xyz, Sep 15, 2026), up from $329M a year earlier.
But the part that’s actually being used is surprisingly small.
Across seven lending venues (including Kamino, Jupiter Lend and Morpho), measured at the protocol level, credit actually lent against tokenized stocks as collateral is about $18.9M.
That’s a penetration rate of 0.65%.
Holding vs. using
This is the framework I’d use for every RWA. It’s just two questions: how much of the asset has been issued, and how much is being used?
The second number is the real measure of the composability story, and the industry almost only ever publishes the first.
To be clear: “using” here means going into DeFi or doing something active onchain. That’s not to say holding has no value. For stocks, holding long term is the core use case. But if holding is all there is, it doesn’t need to be onchain.
FalconX broke down onchain behavior for the top nine tokenized stocks. Holders over 30 days:
| Behavior | Share |
|---|---|
| Purely passive holding | 61.9% |
| Transfers only | 30.3% |
| Traded on a DEX | 7.8% |
Over 30 days, six in ten holders did nothing onchain at all.
Another number pointing the same way: collateral TVL passed $110M at the end of August 2026 (Grayscale; under $10M a year earlier), about 3.8% of the $2.9B stock. Note that this is collateral posted, while the 0.65% above is credit actually lent. The two don’t measure the same thing.
Token Terminal’s breakdown by chain: DeFi TVL in tokenized stocks totals $247.8M, up 1,961% year over year.
| Chain | TVL | Share |
|---|---|---|
| Robinhood Chain | $98.2M | 39.6% |
| Solana | $87.4M | 35.3% |
| BNB Chain | $36.3M | 14.6% |
| Top three combined | $221.7M | 89.5% |
Astonishing growth, still a rounding error in absolute terms.
A comparison that should wake you up
Same period, same assets:
- Transfer volume up 415% month over month
- Outstanding supply up only 1.45%
The tokens are moving violently, but not into financial applications. Transfer volume counts every onchain movement: trades, transfers, custody shuffles, settlement. It went up fourfold, while the share used as collateral is still in single digits.
That’s the clearest gap between the composability story and reality.
Why it’s stuck here
Three reasons, each a specific engineering problem.
-
Pricing when the market is closed has no standard solution. Tokens trade 24/7; the underlying stocks don’t. A geopolitical event hits on a weekend, the token gets sold onchain, the oracle reports the onchain price, and collateral positions in DeFi get liquidated, while the underlying stock’s Friday close hasn’t moved at all. An independent analysis commissioned by the SEC recorded a case where a user bought tokenized NVDA on a DEX at a price 9.3% above the highest price real NVDA traded at on a regulated exchange in the same minute.
-
The wrapper is a new attack surface. A lending market actually has to price four layers at once: the tokenized stock itself, its wrapped version, the vault’s exchange rate, and the oracle path. An attack can happen entirely in the wrapper and oracle layers while the underlying stock price doesn’t move at all. That’s exactly how the Edel incident happened.
-
Retail can’t redeem. Market makers can redeem, so the peg holds. Retail can’t, so the ultimate value of the collateral depends on someone else’s goodwill. Protocols can only set LTVs very low, and that undoes much of the point of using it as collateral.
Someone is already working on it
Kamino has accepted tokenized stocks as collateral since July 2025 and now supports 8 xStocks (SPYx, QQQx, NVDAx, TSLAx, MSTRx and others). Its answer to the first problem is concrete: Chainlink Data Streams for sub-second latency plus real-time market status signals, price bands on weekends and after hours (only accepting quotes within a set range of the last close), and a staleness indicator that responds automatically to trading halts.
It’s the only complete engineering answer to “closed-market liquidation” I’ve seen. By “complete” I mean all four at once: a sub-second price feed, real-time market status signals, closed-market price bands, and halt/staleness handling. Other venues are missing one or two of these, or haven’t disclosed them.
The first product example has also appeared. On September 14, 2026, Kraken launched xStocks Vaults: deposit SPYx, QQQx or NVDAx and earn yield in the same asset (deposit SPYx, earn SPYx), from $1, with a 3-day unbonding period. The stack: Veda for the platform, Sentora as operator, Kamino executing the strategy, Chainlink for prices, Privy for embedded wallets.
In substance, it turns securities lending of tokenized stocks into a retail product.
Traditional brokers have done securities lending for decades, but opaquely. Holders usually can’t see the rate or the revenue split, and often don’t know whether their position has been lent out at all. In this version, the vault, strategy, allocations and performance fee are all public onchain.
What this gap is worth
A simple order-of-magnitude calculation:
- Penetration from 0.65% to 5% = about 8x
- To 10% = about 15x
For a parallel measure from Binance Research: active DeFi TVL grew from $21.6M in January 2026 to $289.1M on September 9, rising from 2.2% to 7.2% of active market cap.
The direction is right. The absolute level is still very low.
Whether this gap gets filled depends on solving the first and second engineering problems, not on how many more stocks get tokenized.
Three lines to close
Issuance measures supply. Usage measures demand. This industry keeps publishing the first.
$2.9B outstanding, $18.9M lent, 0.65% penetration. This is the emptiest gap in the whole sector.
The people who fill it won’t be the ones issuing more tokens. They’ll be the ones who solve closed-market pricing and wrapper risk.
Where do you think that 0.65% will be in a year?
Repost this post?
Share with your followers.
Reply