
Contents (6)

·
Anthropic's Prospectus: Who Gets the $900.9 Billion in Compute Commitments

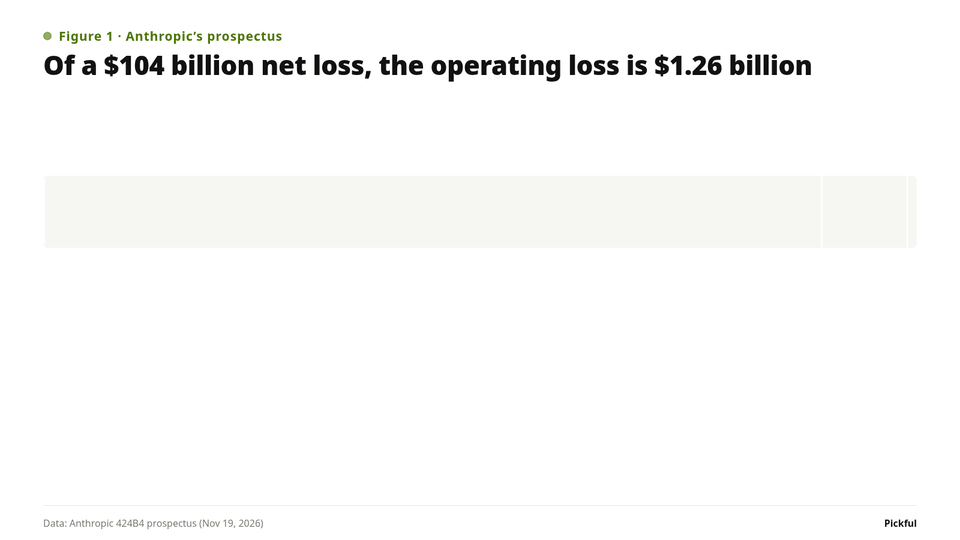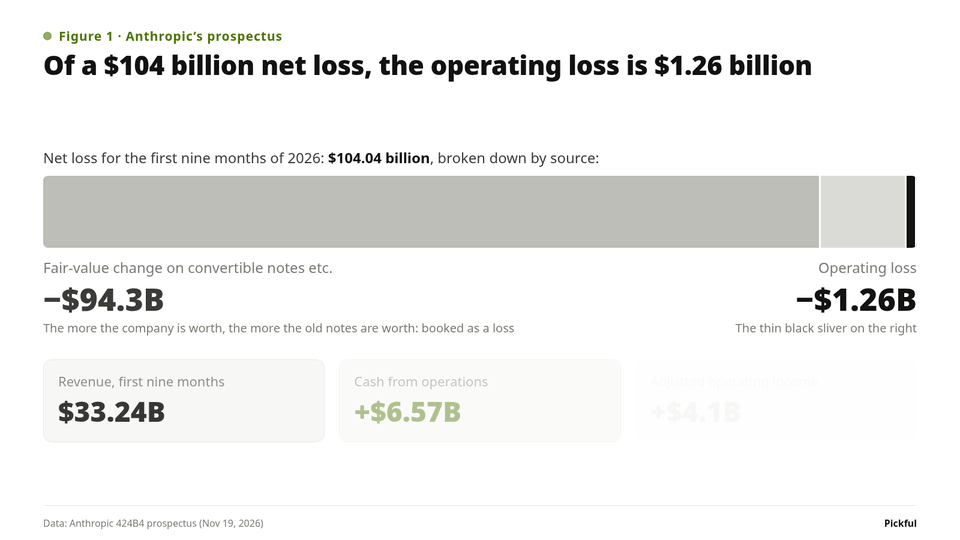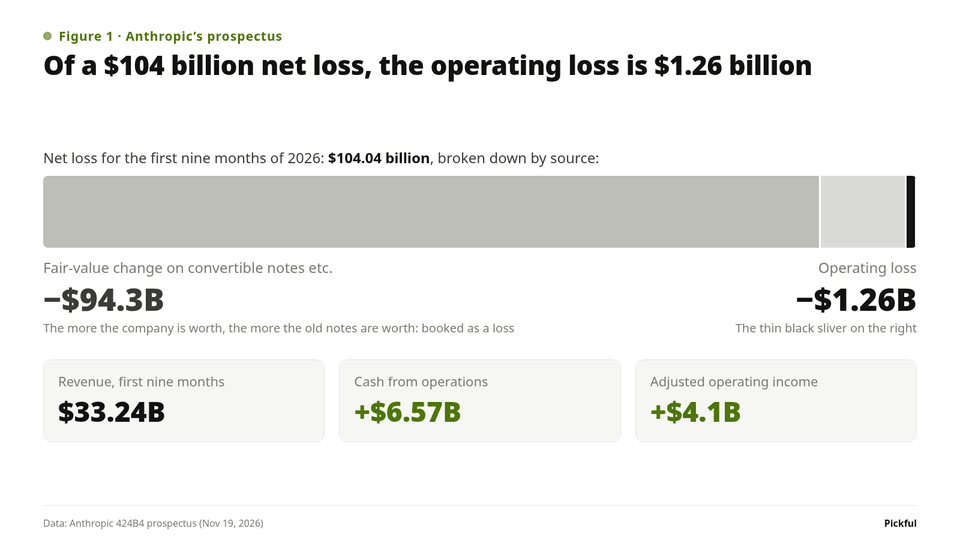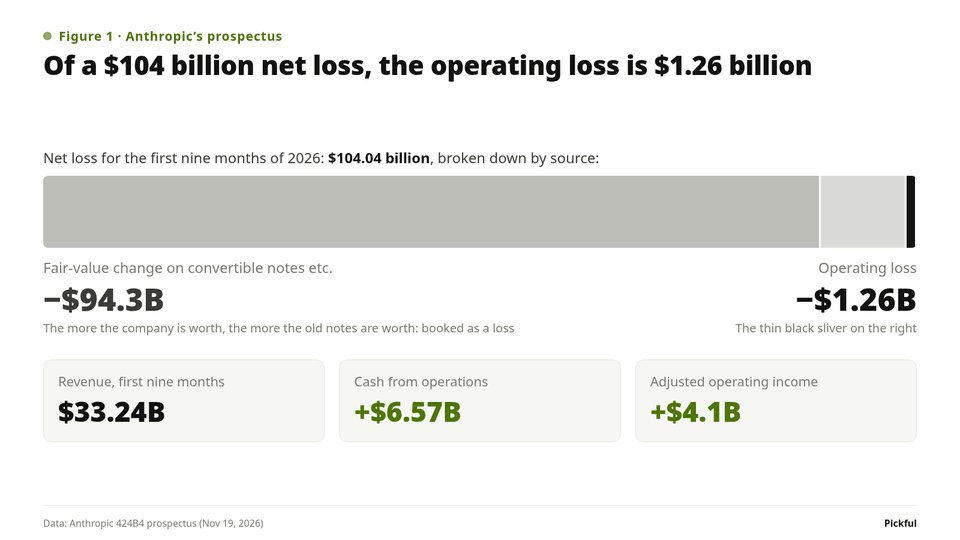
Anthropic went public today. Its prospectus lists about $900.9 billion of compute and infrastructure commitments, close to half with Google, Amazon, Microsoft and Broadcom, which are also its shareholders or lenders. Of a $104 billion nine-month net loss, $94.3 billion is a fair-value remeasurement of convertible notes as the valuation rose; the operating loss was $1.26 billion. After the IPO, some supplier financing converts at market prices, so the share price now affects compute financing.
If you build AI products, run a SaaS business, or invest across the AI supply chain, Anthropic’s Nasdaq debut today is worth more than a glance at the opening price. The part of the prospectus worth your time is the list of compute contracts.
Start with what everyone can see. The shares priced on November 18 at $83, above the earlier $70–78 range. The company and its co-founders sold 980 million shares for a gross offering of $81.34 billion, widely reported as the largest IPO ever. Alongside it came a $26.0 billion private placement bought by seven companies: Google, NVIDIA, AMD, Broadcom, Micron, Microsoft and TSMC. The stock opened today at $111.50, 34% above the offering price.
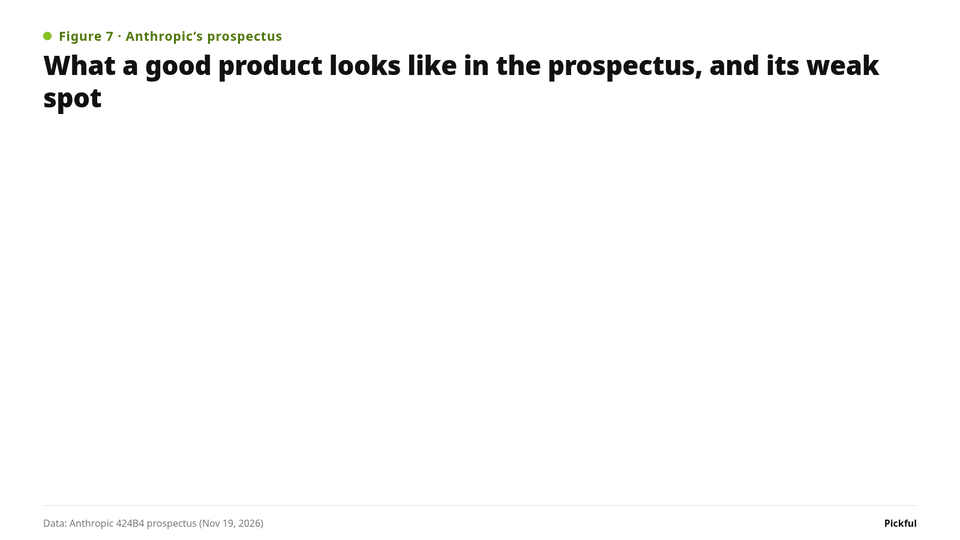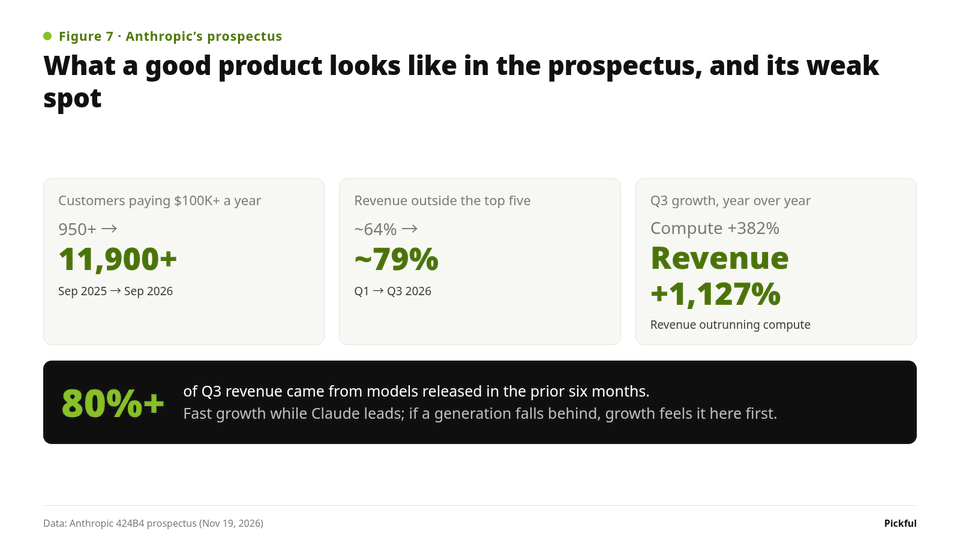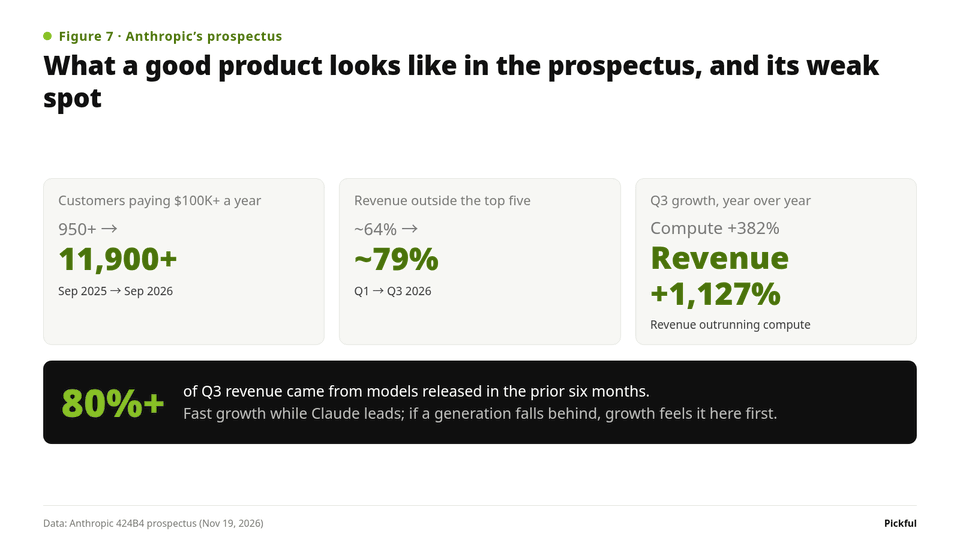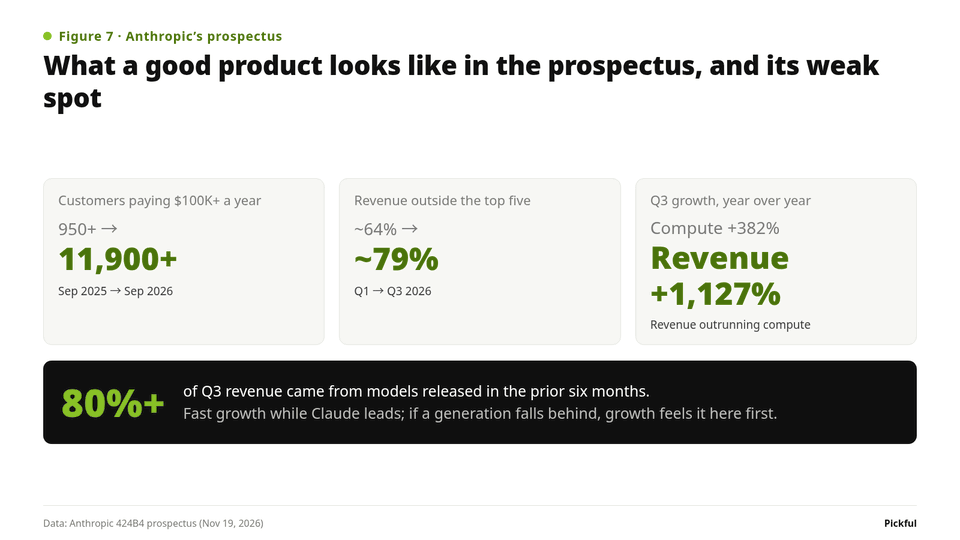
On the product side, the intuition many daily Claude users have holds up in the numbers. Revenue in the third quarter of 2026 was $17.0 billion, up 1,127% year over year. Customers paying more than $100,000 a year went from just over 950 to more than 11,900 in twelve months. Net revenue retention was about 900%: by the prospectus definition, the business customers that were already there a year ago generated about nine times as much revenue this third quarter as in the same quarter last year (individual subscribers excluded).
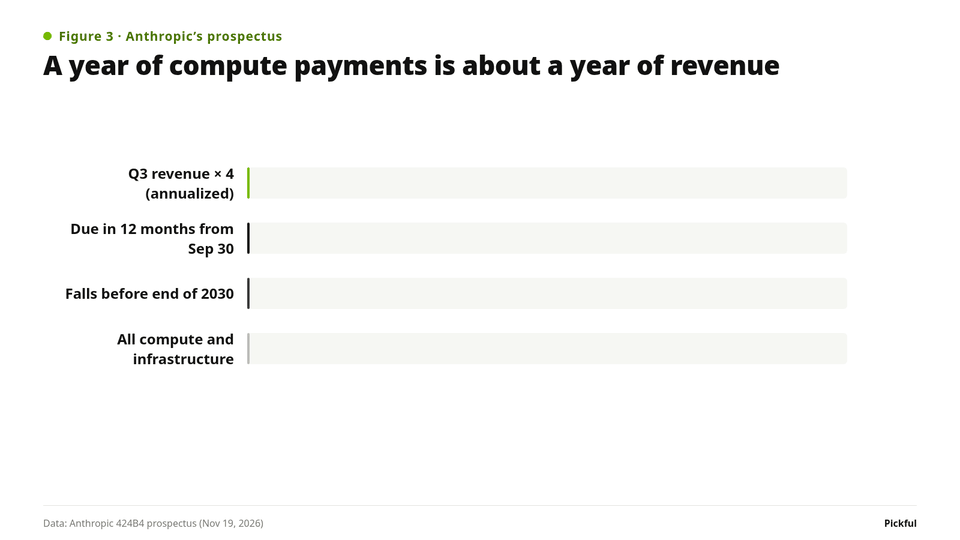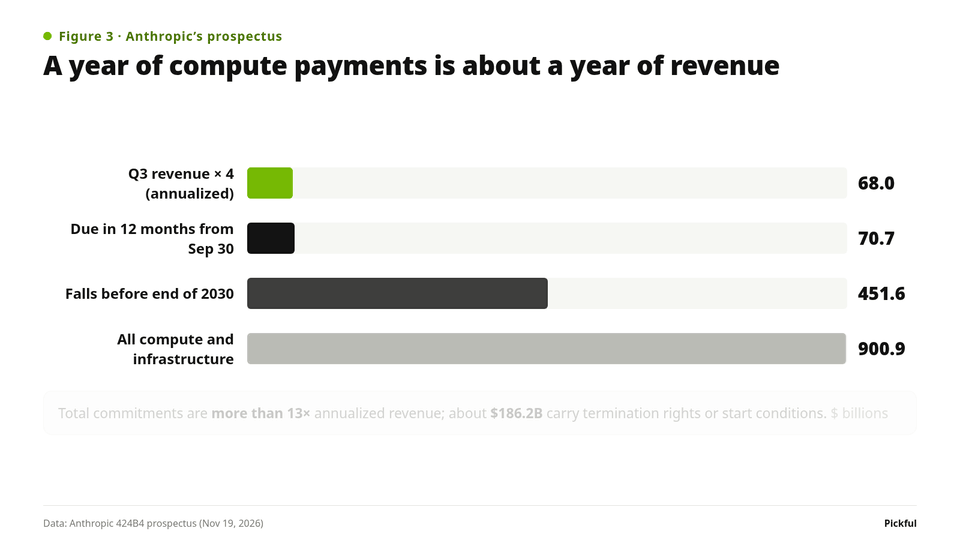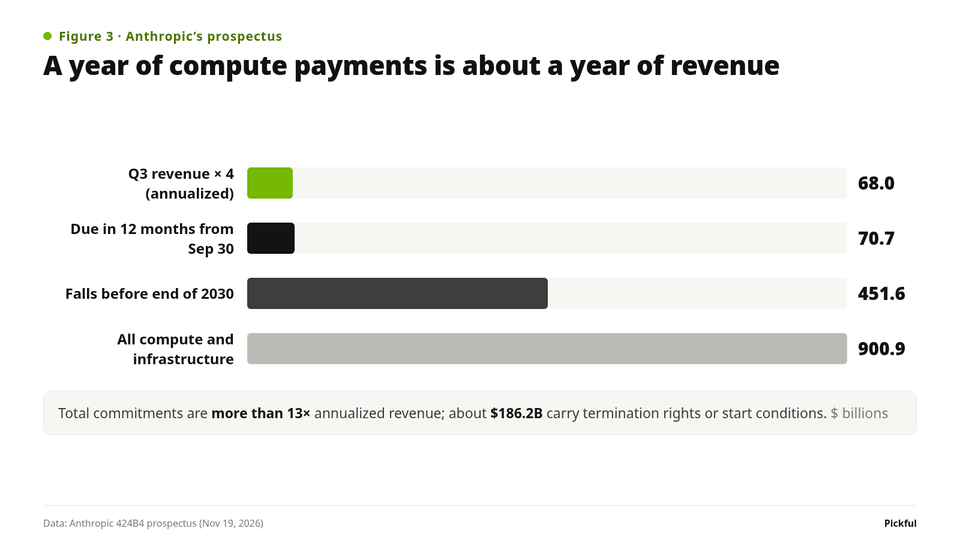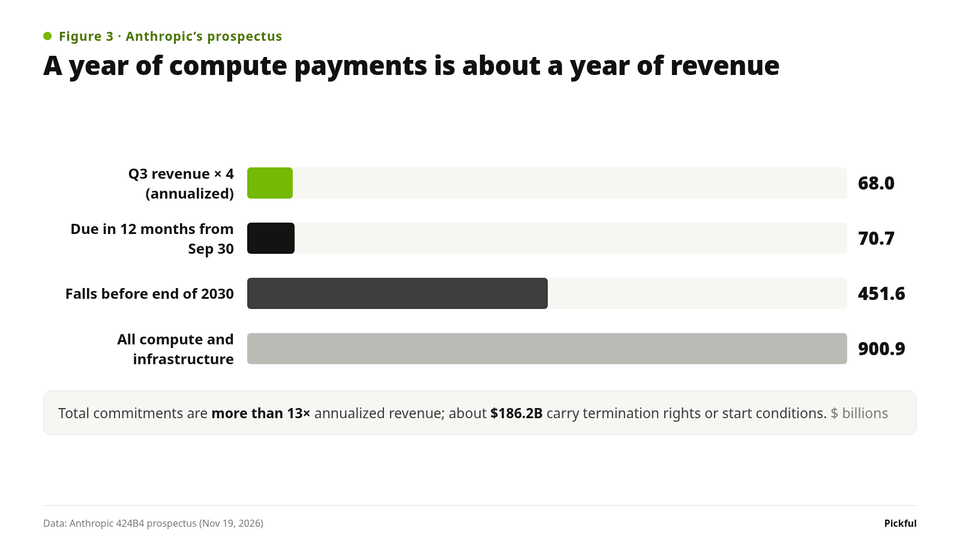
The same prospectus carries another number. Anthropic has signed compute and infrastructure commitments of about $900.9 billion, more than 13 times its annualized third-quarter revenue.
Then look at who those contracts are with. Of the $900.9 billion, contracts tied to Google, Amazon, Microsoft and Broadcom add up to about $439.7 billion, close to half. All four are also Anthropic shareholders or lenders.
First, a misreading: 90% of the $104 billion loss comes from the valuation going up
For the first nine months of 2026, Anthropic’s net loss was $104.0 billion. That number is already making the rounds on social media, usually read as “$33 billion of revenue, $104 billion of losses, the more it sells the more it loses.”
Break the income statement apart and the conclusion runs the other way:
| First nine months of 2026 | $ billions |
|---|---|
| Revenue | 33.24 |
| Operating loss | −1.26 |
| Change in fair value of convertible notes, derivative liabilities and SAFEs | −94.32 |
| Other income (expense), mainly initial recognition and fair-value changes on partner financing arrangements | −10.40 |
| Interest income | +2.36 |
| Income taxes | −0.42 |
| Net loss | −104.04 |
| Cash from operations | +6.57 |
The $94.3 billion fair-value change comes from convertible notes issued in earlier years. This is the easiest line in the whole income statement to misread, so take Amazon as the example.
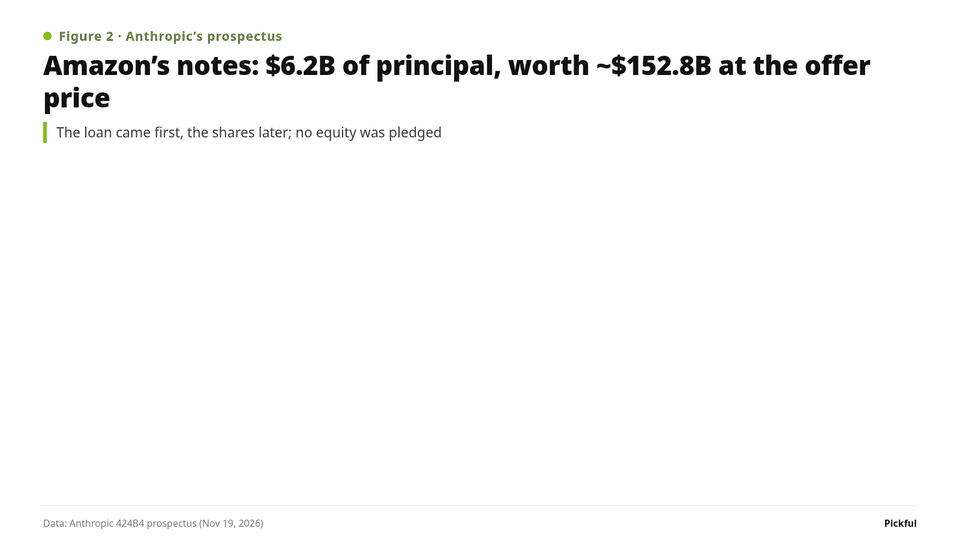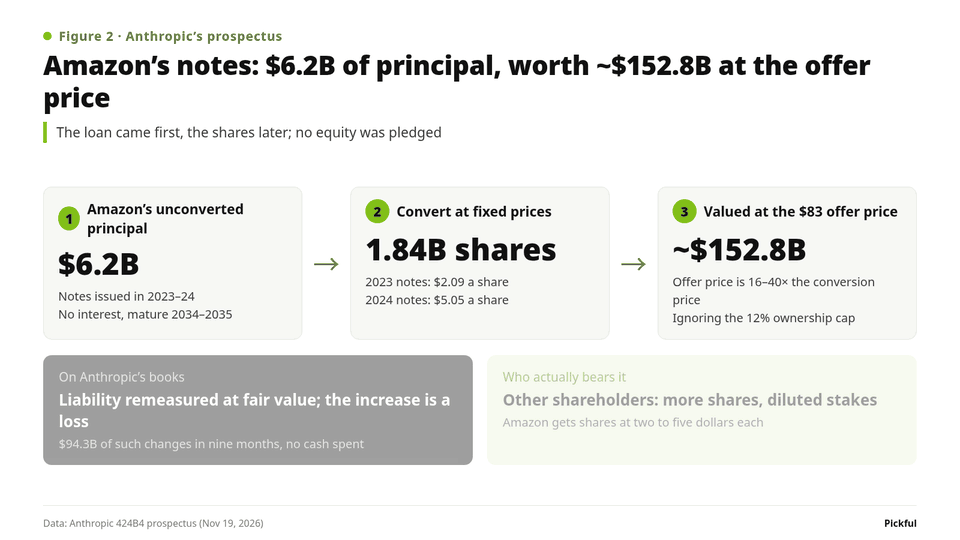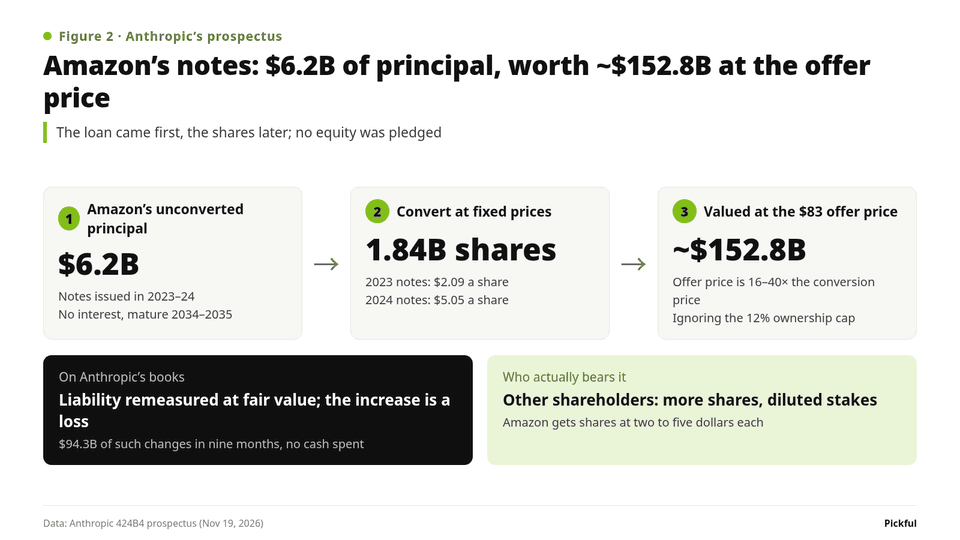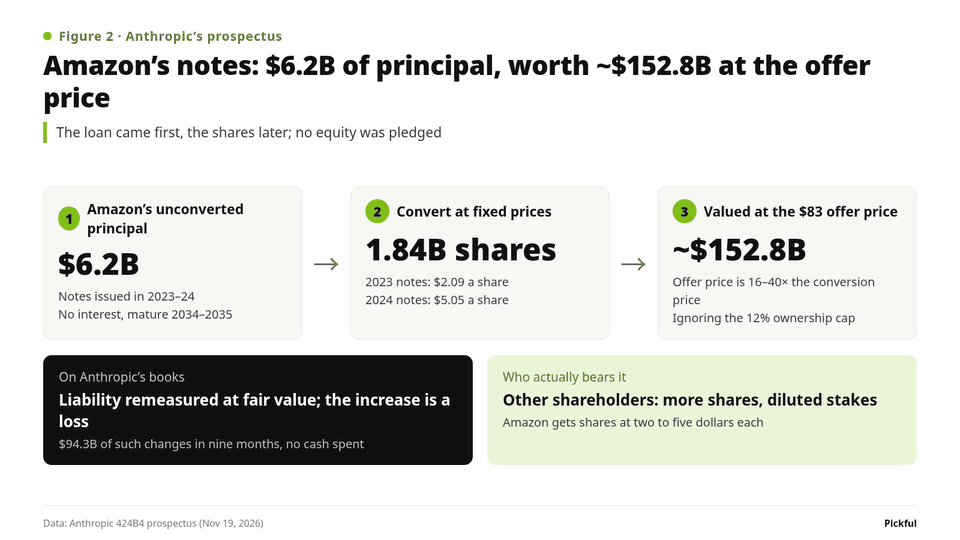
The direction: Amazon lent money to Anthropic and can later turn it into shares. In 2023 and 2024, Amazon lent money to Anthropic and received convertible promissory notes rather than a plain IOU. They carry no interest and mature in 2034–2035. The key term is conversion: Amazon can swap the principal for Anthropic stock at a fixed price, $2.09 a share for the 2023 notes and $5.05 for the 2024 notes. Nothing was pledged, and this is not equity that later turns into debt. The loan came first; the shares come later.
What the IOU is worth depends on what Anthropic is worth. Principal not yet converted stands at $6.2 billion. Ignoring the ownership cap, it converts into about 1.84 billion shares. The $83 offering price is 16 to 40 times the conversion prices, which puts those shares at about $152.8 billion at the offering price. Amazon is not going to ask for $6.2 billion in cash back. It is going to convert.
Why it shows up as a loss. Under the accounting rules, these notes are carried as a liability at fair value and remeasured each period. When the company’s valuation rises, the liability rises with it, and the increase is booked as a loss. The prospectus is blunt: the changes were “primarily driven by an increase in the fair value of our outstanding convertible promissory notes resulting from an increase in our enterprise valuation.” That is where the $94.3 billion for the nine months came from. The booked figure comes from a valuation model period by period and is not the same as $152.8 billion minus $6.2 billion, but it moves the same way: the faster the valuation climbs, the bigger this “loss.”
Who actually bears it. It costs Anthropic no cash; operating cash flow for the nine months was a positive $6.57 billion. Other shareholders bear it. Amazon gets shares for two to five dollars apiece, the share count grows, and everyone else’s percentage shrinks. There is a cap: after conversion Amazon cannot hold more than 12% of capitalization as the prospectus defines it, with the excess rolling into later quarters. That is why about 1.55 billion shares were still unconverted at the IPO.
Put differently, the $94.3 billion on the income statement is, on one side, Anthropic’s valuation rising very fast and, on the other, early investors locking in gains at old prices, with the cost spread across other shareholders.
So the line that matters is operating. For the nine months the operating loss was $1.26 billion, and adjusted operating income, which strips out stock-based compensation and a few other items, was $4.1 billion. Compute and infrastructure expense was $18.8 billion, 57% of revenue. A year earlier the same ratio was 172%: it was spending more than it earned.
Claude’s unit economics are getting better. The question is one layer down: to keep this growth going, how many contracts has Anthropic signed, and with whom?
$900.9 billion of compute commitments, and who they are with
The prospectus puts the total at about $900.9 billion, nearly all of it compute and infrastructure. About $451.6 billion falls before the end of 2030; most of the rest falls between 2031 and 2045. About $70.7 billion is due in the 12 months from September 30, roughly the same as the $68 billion of annualized third-quarter revenue.
That is not all of it. Another group of contracts has no fixed dollar amount, and the prospectus estimates a further $150–175 billion of payments under them, outside the $900.9 billion.
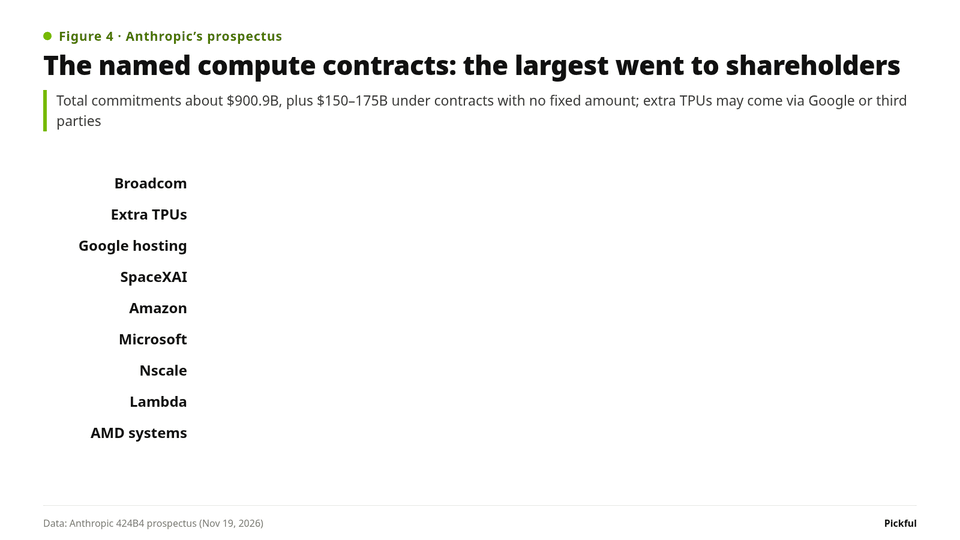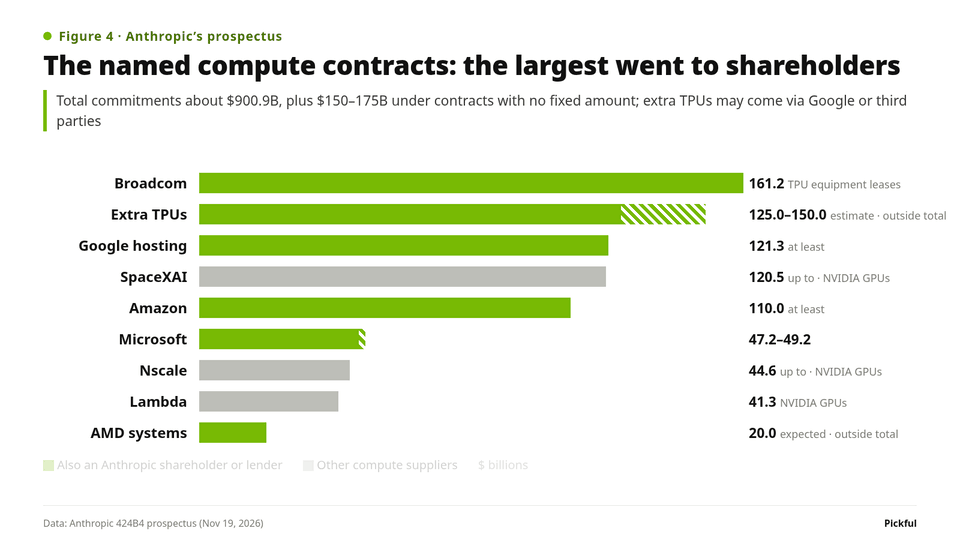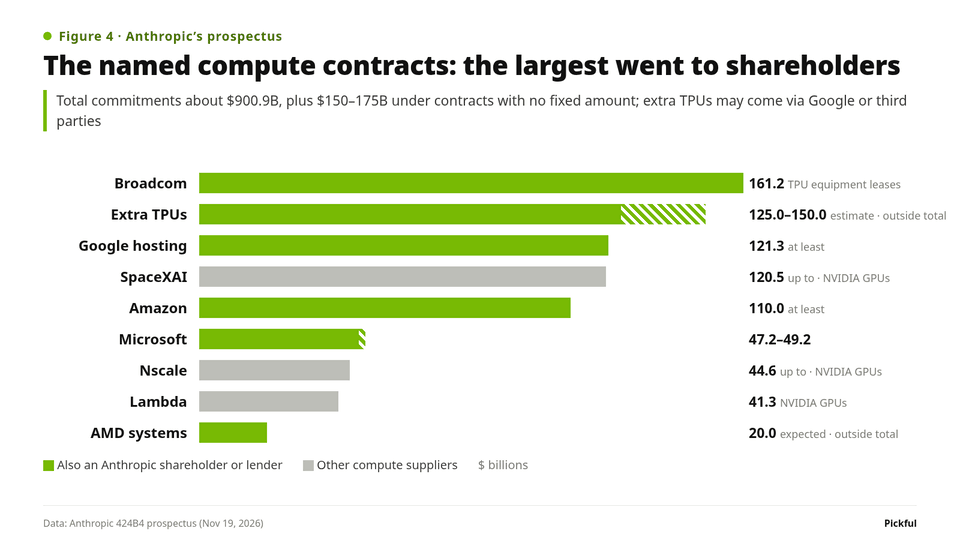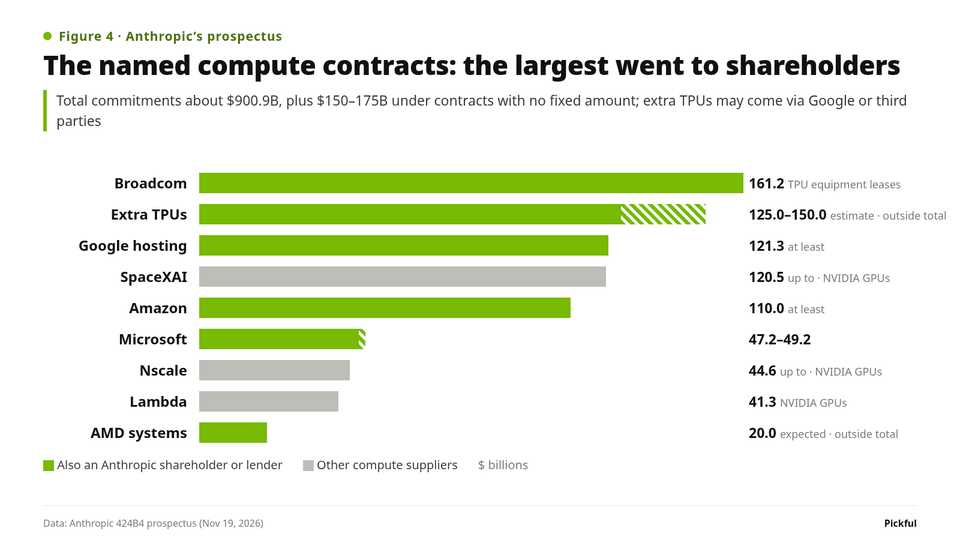
The main contracts the prospectus names:
| Counterparty | What it covers | $ billions |
|---|---|---|
| Broadcom (partly assigned to financing parties) | Five-year equipment leases, TPU compute | about 161.2 (rent, excluding interest) |
| Cloud hosting, April 2026 to July 2033 | at least 121.3 | |
| Additional TPUs (via Google or third parties) | Delivered 2028–2031, outside the $900.9B | est. 125–150 |
| SpaceXAI (formerly xAI) | NVIDIA GPU compute, into 2029 | up to 120.5 |
| Amazon | Cloud services, May 2026 to April 2036 | at least 110.0 |
| Microsoft | Cloud services, November 2026 to June 2033 | 47.2–49.2 |
| Nscale | NVIDIA GPU compute, into 2033 | up to about 44.6 |
| Lambda | NVIDIA GPU compute, into 2034 | about 41.3 |
| AMD systems | Helios racks from 2027; expected spend if the full first tranche is bought, outside the $900.9B | more than 20 |
Two things in this table are worth stopping on.
First, the largest counterparties are also Anthropic’s competitors. Google has Gemini, Microsoft is tied to OpenAI, and SpaceXAI is the xAI that makes Grok. The prospectus says so itself in the risk section: certain of these cloud providers and chip partners “provide us capital or credit support, serve as our infrastructure vendors, and develop and offer AI models and services that compete with ours,” which could create conflicts of interest affecting access to compute, its cost and the prioritization of workloads.
Second, some contracts are less solid than they look. About $186.2 billion of the commitments carry exercisable termination rights or conditions before they start, such as whether the counterparty can secure financing, facilities or approvals. Lambda is the clearest case: a roughly $34.9 billion agreement signed in August is now terminable by either party because Lambda did not secure the facility lease by the agreed date. As of the prospectus, neither side had sent notice.
The same companies in three roles: shareholder, lender, supplier
Put the capital side next to it and the loop becomes clear.
As shareholders. All of the $26.0 billion private placement was bought by suppliers. After the IPO, Google holds about 1.77 billion shares and Amazon about 1.94 billion. Using the prospectus share count, that is about 13.4% and 14.6% of shares outstanding. Amazon has about 1.55 billion more to come as its notes convert. Both hold non-voting Class N shares, with dividend and liquidation rights but no vote.
As lenders. At the end of September, Anthropic had $77 billion of undrawn convertible note capacity: $20 billion from Google (cut to $10 billion once the private placement closes), $15 billion from Amazon and $42 billion from Broadcom. Most of it can be settled in new shares, or converted at the holder’s option, at prices tied to the post-IPO share price. Terms differ by agreement, and some keep cases of cash repayment.
As suppliers. In the contract table above, the largest entries are with these same companies.
AMD is the most direct example. Under the hardware supply agreement signed in July, AMD committed to buy up to $5 billion of Anthropic stock, but not all at once: Anthropic can draw on it as AMD GPUs hit delivery and deployment milestones. AMD’s $2.5 billion in this private placement took half of that commitment off the table. The remaining $2.5 billion only becomes available once milestone amounts exceed the $2.5 billion already paid. Within that cap, the more AMD chips Anthropic deploys, the more AMD stock purchases it can call on.
Broadcom works the same way. The prospectus says the $42 billion note facility can, if needed, fund part of the quarterly rent on TPU equipment leases, and the lessor of that equipment is Broadcom and its financing parties. The notes pay 9% a year and the holder can convert at 90% of the 30-day volume-weighted average price (VWAP); if certain revenue conditions are not met, the rate rises to 13% and the conversion price drops to 85%.
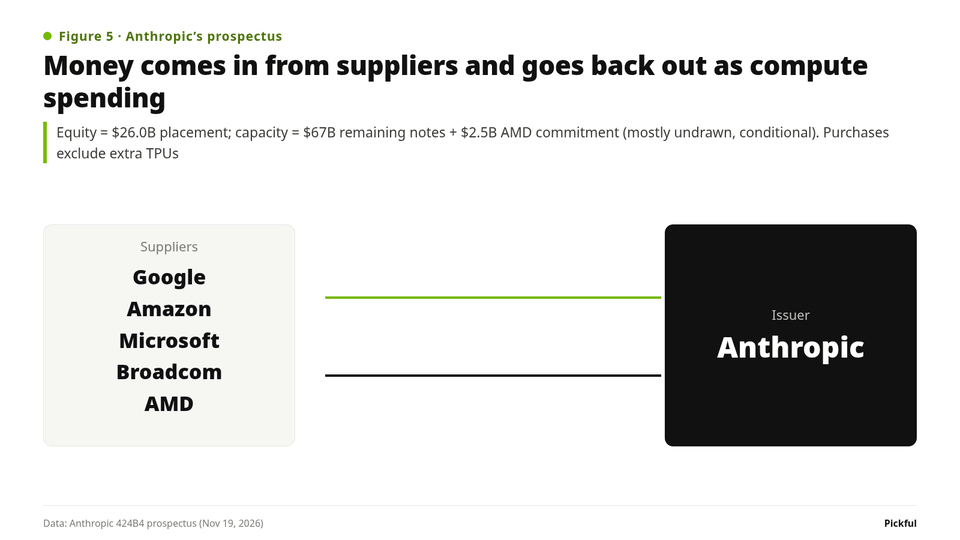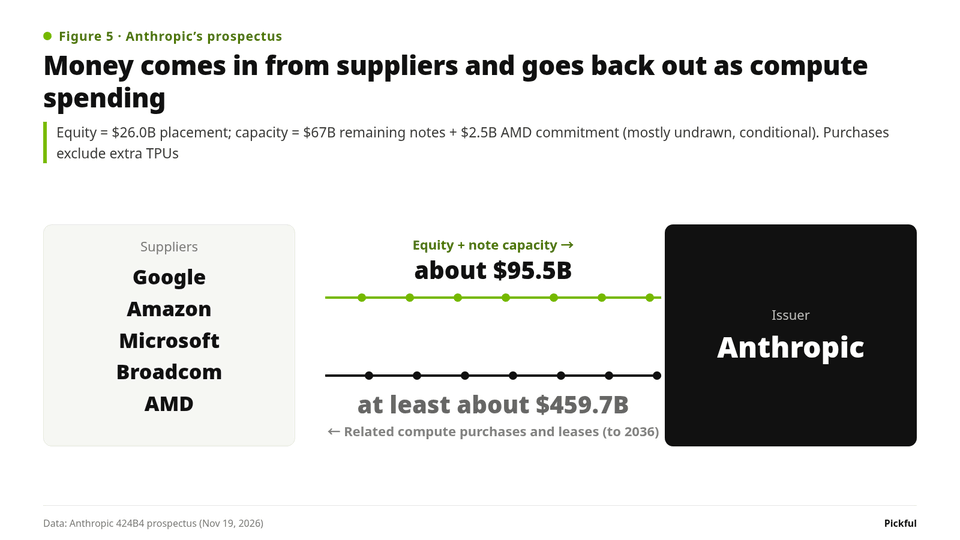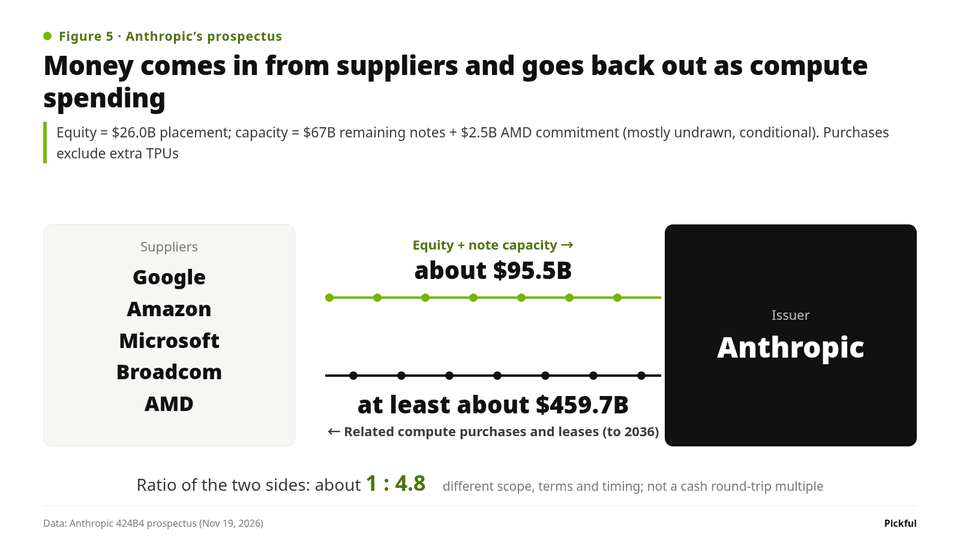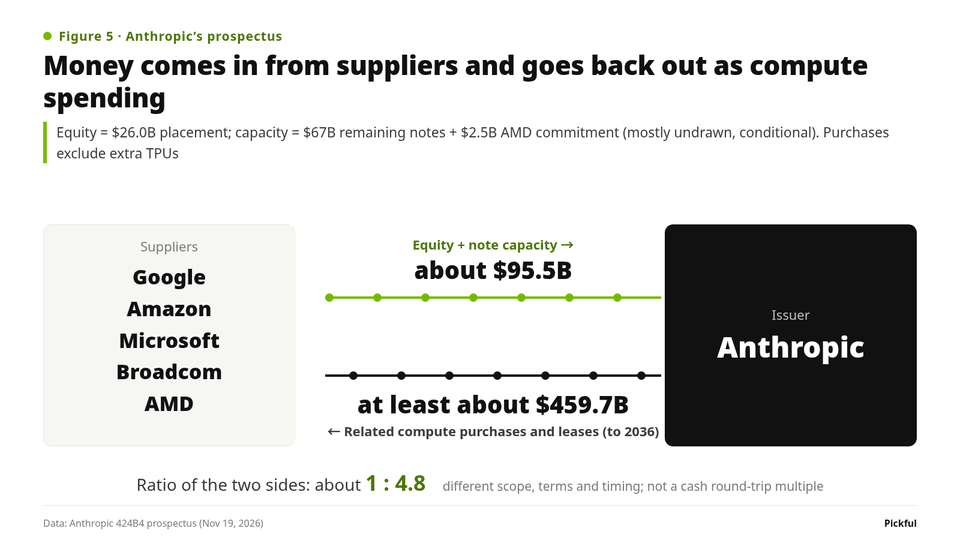
A rough comparison of the two sides: the $26.0 billion placement, plus $67 billion of remaining note capacity and AMD’s remaining $2.5 billion equity commitment, comes to about $95.5 billion. Anthropic’s purchase and lease amounts under contracts tied to Google, Amazon, Microsoft, Broadcom and AMD come to at least about $459.7 billion, before the additional TPUs. The ratio is about 1 : 4.8.
That ratio does not mean “every dollar a supplier puts in comes back as $4.8.” Most of the $95.5 billion is undrawn, conditional capacity. The $459.7 billion mixes fixed commitments, rent that excludes interest and AMD’s expected spend, stretches out to 2036, and part of it is paid to financing parties rather than the suppliers themselves. What it shows is how deep the relationship runs: part of these companies’ revenue over the next decade depends on Anthropic continuing to grow, and they in turn hold a large share of Anthropic’s equity and financing capacity.
After the IPO, the share price starts to affect compute financing
In my view, this is the change from the IPO that matters most for the AI industry.
While Anthropic was private, these equity-for-compute arrangements were priced off each funding round’s valuation and moved every few months. After the IPO, a large part of them is tied directly to the market price:
- AMD’s further stock purchases are priced at the 30-trading-day VWAP before each closing.
- Amazon’s $15 billion 2026 facility converts at the 30-day VWAP on the date the relevant compute capacity milestone is reached.
- Broadcom’s notes convert at 90% (or 85%) of the 30-day VWAP.
- Amazon’s remaining older notes convert each quarter-end at the lowest of the fixed price, the IPO price and the 10-day VWAP. With fixed prices of $2–5, the share price barely matters for these.
That creates a transmission chain that did not exist before. In the arrangements that use market prices, a high ANT share price means a given amount of compute financing needs fewer new shares. If the price falls, more shares are needed, existing holders are diluted further, and there is less room to keep paying for compute this way.
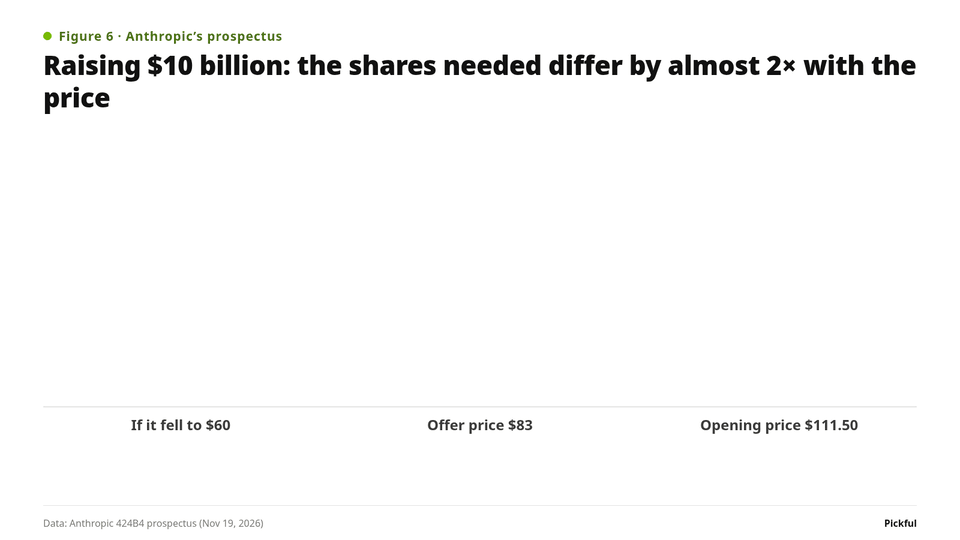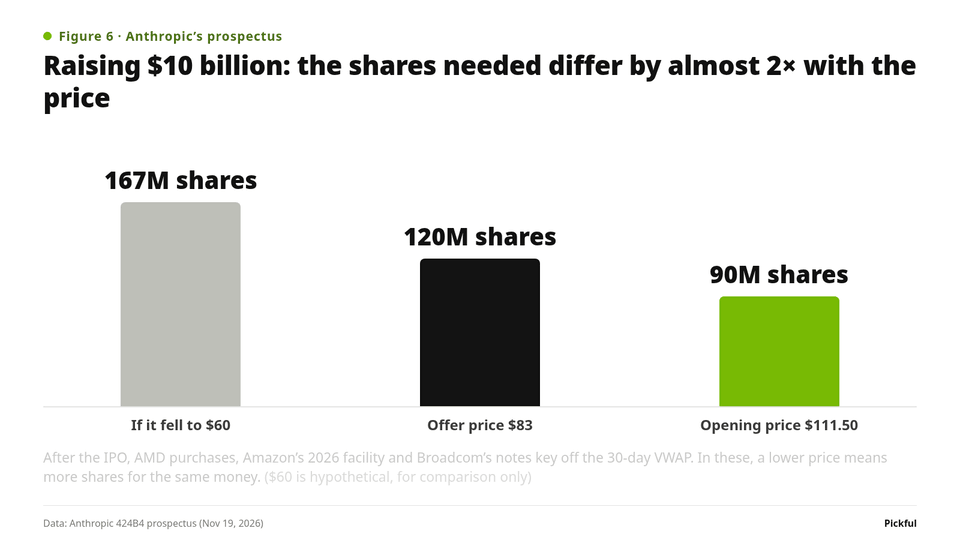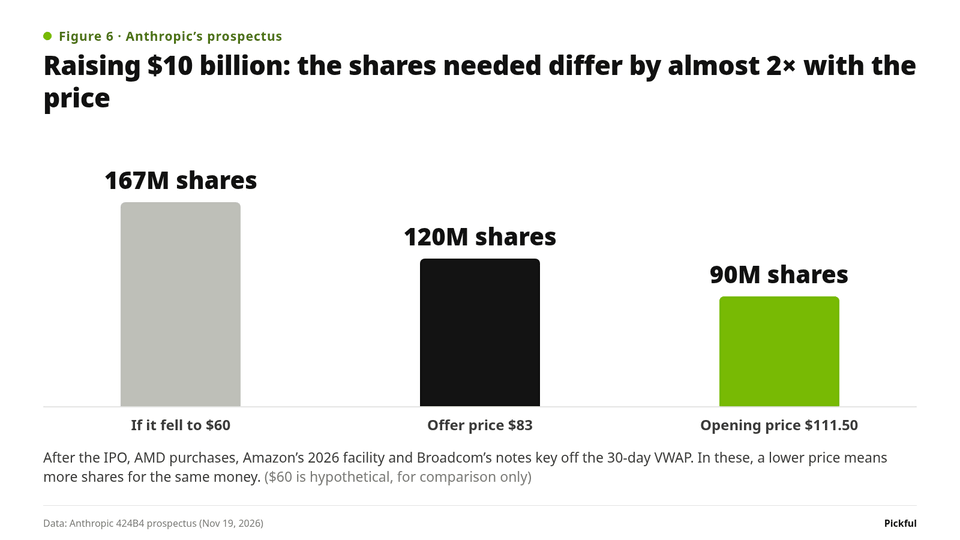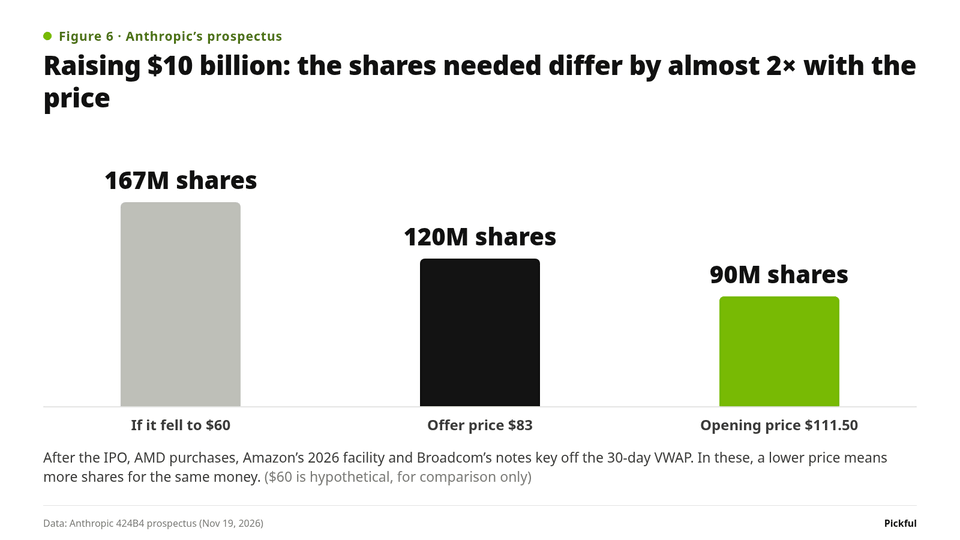
Anthropic has other sources of money, of course: $131.8 billion of cash and short-term investments at the end of September, positive operating cash flow, and a $15 billion revolving credit facility. But supplier financing is large. Forecasts for NVIDIA, Broadcom, AMD and TSMC used to start with cloud providers’ capital spending; from today, the ANT share price belongs in the picture too.
What a good product looks like in the prospectus, and what keeps it good
Back to the opening intuition: Claude is very good and has a lot of room to grow. Three sets of numbers in the prospectus support it.
- Customers are going deeper, not just getting more numerous: in the third quarter, more than half of customers paying over $100,000 a year used both the API platform and at least one first-party application (Claude Code, Claude Cowork and others), up from about 30% at the end of last year.
- Revenue is more spread out: the share coming from outside the top five customers rose from about 64% in the first quarter to about 79% in the third.
- Efficiency is improving: third-quarter revenue grew 1,127% year over year, while compute expense grew 382%.
One number shows both the strength and the fragility: more than 80% of third-quarter revenue came from model versions released in the previous six months. Revenue depends heavily on continually shipping stronger models. While Claude leads, that makes revenue climb fast; if one generation falls behind, growth will feel it here first. The number cannot tell you how quickly customers would switch to another provider; that will take retention data from later quarters.
The other thing to watch is short-term compute. In the third quarter, $5.0 billion of Anthropic’s compute expense came from short-term contracts, which cost far more than multi-year ones. That pulled adjusted operating margin down from 19% in the second quarter to 15%. Add about $2.0 billion of non-cash charges from the donation matching program, and GAAP operating results swung from $974 million of income last quarter to a $567 million loss. Long-term contracts are typically signed 12 to 18 months ahead; when demand outruns them, the gap gets filled at a premium. The prospectus expects short-term compute usage to keep rising in the near term.
Four numbers to watch every quarter
As a public company, Anthropic will report every quarter. For the first time, outsiders can follow a frontier model company’s books quarter by quarter, and OpenAI’s valuation, the risk of AI displacing SaaS companies and chipmakers’ order outlooks will all be measured against it.
If you only track four numbers:
- Compute expense as a share of revenue. 57% for the first nine months, a measure of the overall compute burden. Model efficiency, revenue growth and the timing of new capacity all move it, so read it together with growth.
- Short-term compute spending. $5.0 billion in the third quarter. The bigger it gets, the further demand or research usage is running ahead of long-term capacity, and the more pressure on margins.
- Revenue share from the newest models. Above 80% now, a measure of how much revenue depends on continually shipping new models.
- Supplier facility draws and conversions. How much of the Broadcom, Amazon and Google note capacity and AMD’s equity commitment gets drawn, how many shares are actually issued, and how much unconverted debt remains. The more is drawn, the more compute depends on supplier money.
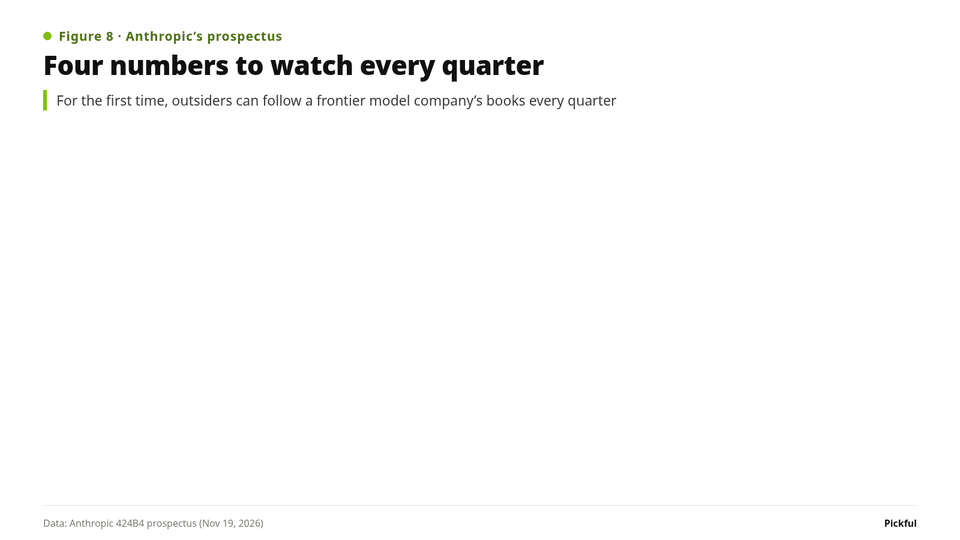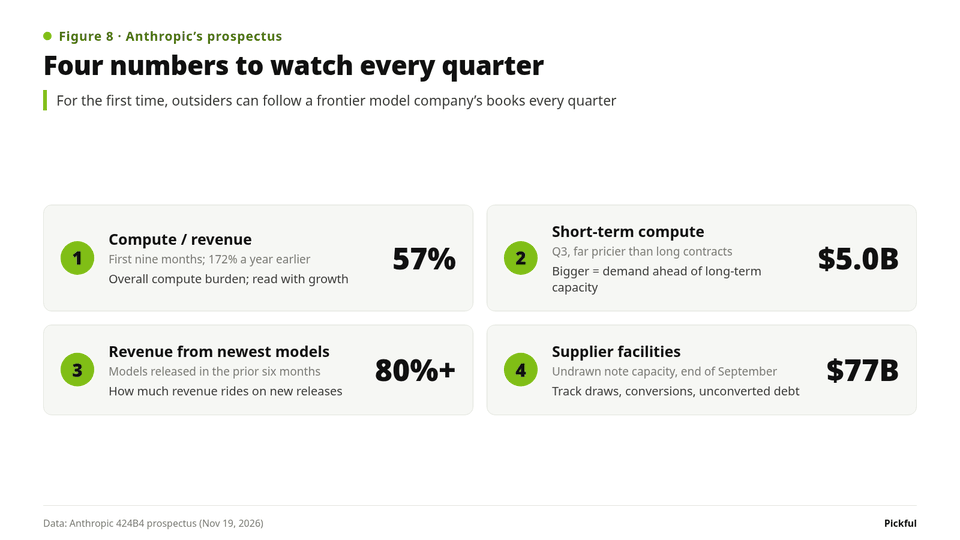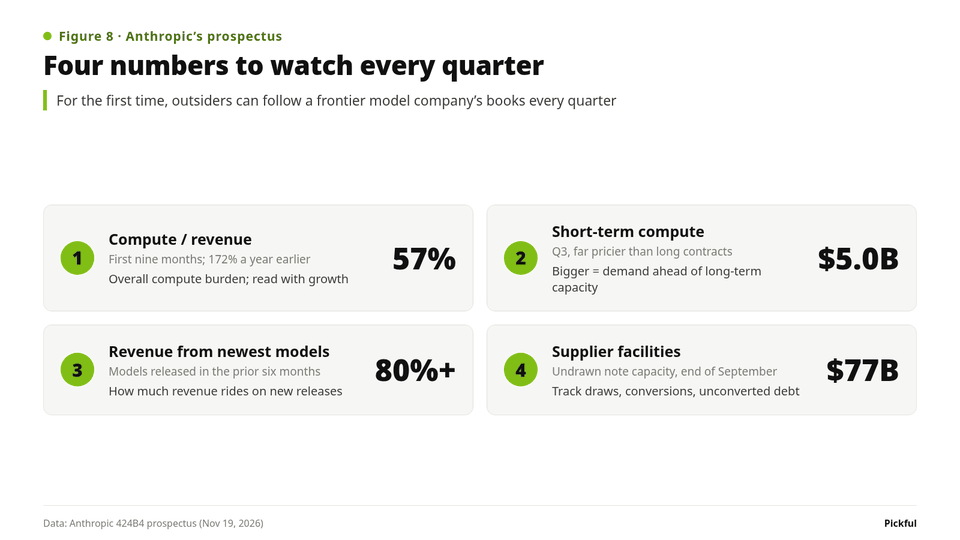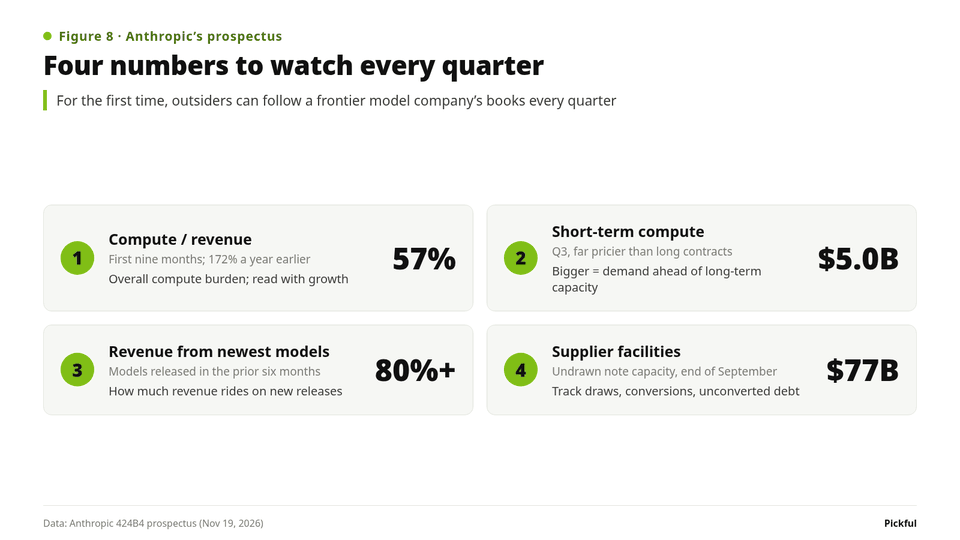
Claude’s product determines how fast revenue can grow, supplier money determines how much compute can be built, and the ANT share price affects what that money costs. The three are locked together, and each quarter’s report will show which one loosens first.
Which of these four numbers do you think breaks first?
Sources
- Anthropic 424B4 prospectus (Nov 19, 2026): revenue, income statement, cash flows, net revenue retention definition, the $900.9 billion of commitments and individual contracts, convertible note facilities and conversion terms, the AMD agreement, Amazon and Google holdings, customer and revenue concentration, short-term compute, cash and credit facility.
- Anthropic pricing free writing prospectus (Nov 19, 2026): $83 offering price, 980 million shares, $81.34 billion, $26.0 billion private placement (313,253,007 shares).
- $70–78 range, “largest IPO ever,” $111.50 opening price: same-day reporting by CNBC, CNN, StockTitan and Fortune.
- Ownership percentages are our own calculation from the prospectus post-IPO share count (7.583 billion Class A plus 5.637 billion Class N, before the underwriters’ option). They are economic interest in shares outstanding, not voting power or fully diluted.
- The 1 : 4.8 ratio is our own sum. Purchase side: Google hosting 121.3 + Amazon 110.0 + Microsoft 47.2 (low end) + Broadcom rent 161.2 + AMD 20 (expected, low end). Capital side: placement 26.0 + remaining note capacity 67 + AMD remaining equity commitment 2.5. The two sides differ in scope, conditions and timing.
Repost this post?
Share with your followers.
Reply